Näherinnen in einer Textilfabrik – Symbolbild für die Zwangsarbeit-Verordnung für Lieferketten
23.09.2026

EU Forced Labour Regulation: What Companies Need to Know Now

In 2027, the new European regulation on forced labour will start to apply, prohibiting products made with forced labour from being made available on the EU market or exported from the EU. Here’s our summary of what’s behind it – and what it means for your supply chain.

The EU Forced Labour Regulation (FLR) prohibits products made with forced labour from being made available on the EU market or exported from the EU as of December 14, 2027. It applies to all companies, regardless of size or industry. It doesn’t require a report. In the event of suspicion, however, companies must be able to provide information about their supply chain.

The European Commission’s guidelines have been available since fall 2026. They show in much greater detail how authorities will conduct their investigations and what information companies should have ready. We summarize what the regulation says, what the guidelines add, and where it’s best to start.

What is the Forced Labour Regulation

The EU Forced Labour Regulation (Regulation (EU) 2024/3015) prohibits products made wholly or partly with forced labour. It has been in force since December 2024 and will apply from December 14, 2027. From that date on, such products may no longer be placed on the EU market, made available on it, or exported from the EU.

The ban covers all products, whether they originate in the EU or in third countries. It also applies to components and intermediate products: if forced labour was used at any stage – during extraction, harvesting, production, or processing – the final product falls under the ban. Services are not covered.

Unlike the LkSG and CSDDD, the regulation doesn’t require companies to follow specific due diligence processes or publish an annual report. Instead, it focuses on the outcome: a product made with forced labour must not be sold. The burden of proof lies with the authorities. If the suspected forced labour takes place outside the EU, the European Commission leads the investigation; within the EU, the competent national authority is responsible.

Since June 2026, the European Commission’s Forced Labour Single Portal has brought together all information on the regulation, including guidelines, contact points, and support services.

What counts as “forced labour”?

The regulation adopts the definition used by the International Labour Organization (ILO): “Forced labour is all work or service which is exacted from any person under the menace of any penalty and for which that person has not offered themselves voluntarily. This includes state-imposed forced labour.”

In practice, forced labour is rarely as obvious as the term suggests. The ILO indicators of forced labour help identify warning signs:

  • Exploitation of vulnerable persons
  • Deception
  • Restriction of freedom of movement
  • Insulation
  • Physical and sexual violence
  • Intimidation and threats
  • Retention of identity documents
  • Withholding of wages
  • Debt bondage
  • Abusive working and living conditions
  • Excessive overtime

Many of these indicators don’t show up on any supplier data sheet. They usually only become visible when companies ask targeted questions, for example through self-assessments, audits, or grievance mechanisms.

Does the Forced Labour Regulation also apply to mid-sized companies?

Yes. The regulation applies to every company that places products on the EU market, makes them available there, or exports them from the EU, including online retailers based in third countries. There are no thresholds based on headcount or revenue.

This is a significant difference from the LkSG and CSDDD: with fewer than 1,000 employees, or fewer than 5,000 employees in the future, many mid-sized companies aren’t directly affected by these laws and therefore haven’t set up their own due diligence processes. Under the Forced Labour Regulation, the only thing that matters is whether a product is affected.

The Walk Free Foundation’s 2023 Global Slavery Index shows how relevant the issue is for Germany: in the five largest product categories alone, Germany imported goods worth USD 44 billion that carry a risk of forced labour. Many of these goods enter mid-sized manufacturers’ supply chains as raw materials or intermediate products.

On top of that comes pressure from customers. Large manufacturers will want to know where the components in their products come from – and will pass this question on to their suppliers.

The European Commission has announced targeted support for smaller companies. A checklist and an overview of freely available supply chain tracing tools are already available on the Single Portal.

What do the European Commission’s guidelines say?

The guidelines show how authorities will apply the regulation and how companies can reduce their risk through due diligence processes. The Commission adopted them on June 26, 2026. They aren’t legally binding, but they give companies and authorities clear direction.Die Leitlinien zeigen, wie Behörden die Verordnung anwenden werden und wie Unternehmen mit Sorgfaltsprozessen ihr Risiko senken können. Die Kommission hat sie am 26. Juni 2026 angenommen. Rechtlich bindend sind sie nicht. Sie geben Unternehmen und Behörden aber eine klare Orientierung.

The key points:

  • OECD-based due diligence: The regulation doesn’t create any new due diligence obligations. Nevertheless, the guidelines are based on the OECD’s six-step due diligence framework. Companies that align their measures with this framework will be in a better position to demonstrate what they have done to prevent forced labour if suspicions arise.
  • Risk-based assessment: Authorities prioritize cases based on the scale and severity of the forced labour, the quantity of products placed on the EU market, and the share the suspect component accounts for in the product. Risk factors related to regions, sectors, and companies are also taken into account, as is the quality of a company’s due diligence processes.
  • Designated contact: Companies should appoint a person or department responsible for handling inquiries from authorities.
  • Remediation: If forced labour occurs, companies should be prepared to contribute to remediation. If this isn’t realistic in the short term, responsible disengagement from the business relationship may be the only option.
  • Support for smaller companies: The Commission has published a checklist and an overview of freely available tracking tools. Between September and November 2026, it is also offering webinars, some of them sector-specific.

What happens when authorities investigate a suspected case?

In the event of suspicion, the authority requests information on the measures a company takes to identify and address forced labour risks in its supply chain. This may include supplier lists, proof of origin, or the results of risk assessments. With the consent of the company and the country concerned, the authority can also conduct inspections outside the EU.

If a company is unable or unwilling to provide the information, the authority makes its decision based on the information available to it. In practice, this rarely works in the company’s favor.

If the suspicion is confirmed, the authority can order:

  1. that the product may no longer be placed on the EU market, made available on it, or exported from the EU
  2. that products already made available be withdrawn from the market,
  3. that affected products be disposed of at the company’s expense or that tainted components be replaced.

For supply chains of strategic importance, the authority can instead have the product withheld until the company demonstrates that the forced labour has been eliminated. Products that have already reached end users don’t have to be recalled.

An authority’s decision applies in all EU member states, and customs authorities enforce it at the border. Companies face fines if they fail to comply with such a decision.

How does the Forced Labour Regulation differ from the CSDDD and LkSG?

The LkSG and CSDDD require large companies to implement due diligence processes. The Forced Labour Regulation focuses on the product and applies to all companies.

LkSG CSDDD Forced Labour Regulation
Legal form German law EU directive, transposed into national law EU regulation, directly applicable
Applies from 2023 July 2029 December 14, 2027
Approach Company-based Company-based Product-based
Who is affected? Planned increase to 5,000 employees and €1.5 billion in revenue Companies with more than 5,000 employees and more than €1.5 billion in global revenue All companies that place products on the EU market, make them available there, or export them from the EU
Topics Human rights and the environment Human rights and the environment Forced labour
What is required? Due diligence processes and internal documentation Due diligence processes No process requirement, but forced-labour-free products
Legal consequences Fines, only enforced for serious violations since fall 2025 Fines of up to 3% of global revenue Market ban, withdrawal, disposal; fines for non-compliance

The three regulations interlock. Companies that have already set up due diligence processes for the LkSG or CSDDD can build on them. What’s needed then is primarily a closer look at individual products, raw materials, and regions of origin.

Where should supply chain managers start?

There’s enough time until December 2027 to build processes without rushing. It’s best to start where the risk is highest and your information is thinnest.

1. Identify critical products and raw materials: Which raw materials and intermediate products come from regions or sectors with an elevated risk of forced labour? The ILO indicators and, in the future, the Commission’s risk database provide guidance.

2. Review existing supplier information: What do you already know about these suppliers today? Self-assessments, certificates, and supporting documents are often scattered across the ERP system, Excel spreadsheets, and individual inboxes.

3. Clarify responsibilities: Who would be the point of contact if an inquiry from the authorities comes in? And who would then compile the information?

4. Connect to existing processes: Integrate the topic into procurement, compliance, and supplier management rather than setting up a separate process alongside them.

5. Involve suppliers: Communicate your expectations, for example through a code of conduct and targeted questions in supplier surveys.

How does VERSO support companies in implementing the Forced Labour Regulation?

In the event of suspicion, what matters is that you can present your supplier information quickly and transparently. The VERSO Supply Chain Hub maps these processes.

With our due diligence processes, you can survey your suppliers in a structured way, assess risks, and manage measures. All self-assessments, supporting documents, and steps are documented in one place instead of being scattered across inboxes and spreadsheets. This also shows you which suppliers you’re still missing information from.

VERSO has been supporting mid-sized companies in implementing sustainability since 2010, including in their supply chains. Feel free to get in touch if you’d like to know how to integrate the Forced Labour Regulation into your processes.

FAQ on the EU Forced Labour Regulation

When does the EU Forced Labour Regulation apply?

The regulation has been in force since December 2024 and will apply from December 14, 2027. From that date on, products made with forced labour may no longer be made available on the EU market or exported from the EU.

Does the Forced Labour Regulation also apply to mid-sized companies?

Yes. The regulation has no thresholds based on headcount or revenue. For smaller companies, the European Commission has published a checklist and an overview of freely available tools.

Do I have to prepare a report under the Forced Labour Regulation?

No. The regulation provides for neither an annual reporting obligation nor a general audit requirement. In the event of suspicion, however, companies must provide the authority with information about their supply chain and the measures they have taken.

Are the European Commission’s guidelines binding?

No. The guidelines were adopted in June 2026 and published in the EU’s Official Journal in September 2026. They serve as guidance for companies and authorities; only the text of the regulation itself is legally binding.

Who checks whether a product is affected?

If the suspected forced labour takes place outside the EU, the European Commission is responsible; within the EU, the national authorities are. The burden of proof lies with the authorities. Which authority will be responsible in Germany has not yet been determined.

What is the difference between the Forced Labour Regulation and the LkSG?

The LkSG requires companies with 1,000 or more employees to implement due diligence processes. The Forced Labour Regulation focuses on the product: it applies to all companies and excludes affected products from the EU market.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Current ESG topics and legislative changes
  • Individual advice from the VERSO experts
  • News about VERSO
  • Sustainability Events and more
Ältere Frau arbeitet am Laptop und guckt sehr konzentriert
19.08.2026

ESG sanctions at a glance: the cost of mistakes in reporting and supply chain obligations

A slap on the wrist and, if it becomes public, a brief outcry from the public: until a few years ago, companies didn’t have to worry too much if they put sustainability on the back burner or engaged in greenwashing. The Omnibus package does little to change that: the EU has pushed back deadlines and reduced the number of companies affected, but it has not abolished the sanctions.

Companies that breach ESG and supply chain obligations risk fines in the millions, penalties calculated as a percentage of annual turnover, seized goods or exclusion from public contracts, depending on the regulation. The EU Omnibus package made some rules less strict in 2026 and narrowed the group of companies they apply to. This article shows which sanctions apply under the CSRD, CSDDD, LkSG, CBAM, EUDR, PPWR, DPP and EmpCo, and from when.

As of September 2026. This article reflects the EU Omnibus I package, the planned reform of the LkSG and the latest postponement of the EUDR. This information is editorial content that should not be construed as legal advice. VERSO accepts no liability.

ESG sanctions at a glance: possible sanctions, companies affected and start date by regulation (as of September 2026)
Regulation Possible sanctions Who is affected? From when?
CSRD Planned under the HGB: fines of up to €10 million or 5% of annual turnover (capital market-oriented companies), prison sentences of up to 3 years More than 1,000 employees and over €450 million net turnover Once the German implementation act enters into force (legislative process ongoing)
CSDDD Up to 3% of global net turnover, civil liability under national law More than 5,000 employees and over €1.5 billion net turnover Applies from 26 July 2029
LkSG Previously up to €8 million or 2% of global annual turnover, exclusion from public procurement; in future only for serious violations 1,000 or more employees in Germany In force since 2023, reform in the legislative process
EU ETS €100 per tonne of CO₂e without an allowance (adjusted for inflation) Operators of installations covered by emissions trading In force
CBAM Same as EU ETS per missing certificate, revocation of declarant status Importers of 50 tonnes or more of CBAM goods per year Definitive phase since 1 January 2026
EUDR At least 4% of annual EU turnover, confiscation of goods, import bans, exclusion from public procurement Operators and traders handling relevant commodities 30 Dec 2026 (large/medium), 30 June 2027 (micro/small)
PPWR Fines of up to €200,000 under the German VerpackDG, distribution bans, public register entries Manufacturers, importers and distributors of packaging Since 12 August 2026
EmpCo Warning letters, cease-and-desist claims; fines of up to €50,000 or 4% of the affected annual EU turnover All companies making environmental claims to consumers Since 27 September 2026
DPP (ESPR) Fines (level set nationally), withdrawal and recall, import bans, exclusion from public procurement Manufacturers and companies placing the relevant product group on the market Battery passport from 18 Feb 2027, other product groups to follow

Stress-free CSRD compliance

Make CSRD as easy as possible: Our new CSRD Suite provides tools and support for every stage of CSRD compliance.

What sanctions apply for breaches of the CSRD, EU Taxonomy and SFDR?

There is no EU-wide, uniform set of sanctions for the CSRD. Each member state decides how to penalise errors in sustainability reporting. In Germany, this will be governed by the CSRD Implementation Act, which is still going through the legislative process. Until it enters into force, companies that were already required to report remain subject to the HGB rules on the non-financial statement. The government draft is based on the existing criminal and administrative penalty provisions in §331 and §334 HGB. In figures, this means:

  • Prison sentences of up to 3 years
  • For members of authorized representative bodies or supervisory boards of a corporation: prison sentences of up to 3 years; companies face fines of up to 2 million euros or twice the economic benefit they have derived from the incorrect report – whichever is higher.
  • For capital market-oriented companies: Fines of up to 10 million euros, 5 percent of annual turnover or twice the economic benefit – the highest amount is also chosen here.

On top of this – as the fermented icing on the cake, so to speak – there may also be legal action for breach of competition law, exclusion from public procurement procedures and “naming and shaming”, i.e. publicity including loss of reputation.

Important to know: Only intentional errors and errors due to gross negligence are punishable.

In the next few years, the first court proceedings will show the exact direction of sanctions for breaches of the EU taxonomy, CSRD and SFDR.

Read more:

Practical guide to CSRD

Our practical guide, including a checklist, will help you prepare for CSRD reporting.
Find out what challenges there are and how you can overcome them.

Sanctions for LkSG and CSDDD

How high are the fines under the CSDDD?

With the Omnibus I package, the EU significantly weakened the CSDDD, the European supply chain directive, in 2026. This also affects the sanctions. Companies that breach their due diligence obligations for people and the environment face:

  • Fines of up to 3% of global net turnover.
  • Civil liability for damages. The EU-wide harmonised liability rule was removed; liability is now governed by the law of each member state.
  • Naming and shaming and exclusion from public procurement.

What does a breach of the German Supply Chain Act (LkSG) cost?

In contrast to the CSDDD, the German Supply Chain Act does not create its own civil liability. The LkSG requires companies to meet human rights and environmental due diligence obligations in their own business operations and towards direct suppliers. For indirect suppliers, the obligations apply as soon as the company has substantiated knowledge of possible violations. Risks must be identified, documented and eliminated or at least minimised.

Previous fine framework: fines of up to 8 million euros. For companies with an annual turnover of more than 400 million euros, the fine increases to up to 2% of global annual turnover. And: companies can be excluded from public procurement.

What is set to change: in September 2025, the German government adopted a reform of the LkSG; the legislative process is still ongoing. Under the reform, the annual reporting obligation is to be abolished retroactively. Fines are only to be imposed for serious violations that lead to grave human rights abuses. The due diligence obligations themselves remain in place. In practice, the Federal Office for Economic Affairs and Export Control (BAFA) has already suspended the reporting obligation. In the medium term, the national implementation of the CSDDD is to replace the LkSG.

Read more:

EU ETS and CBAM sanctions

EU ETS

With the EU Emissions Trading System (EU ETS), the EU aims to cap the emissions of the member states. Companies only have a certain amount of freedom to emit emissions – otherwise certificates must be purchased. Non-compliance could result in fines:

  • 100 euros per metric ton of CO2 equivalents emitted without a certificate (adjusted annually for inflation)

In order to avoid certificate prices on the one hand and sanctions on the other, some companies relocated their production to non-EU countries (“carbon leakage”). The CBAM was therefore also introduced as part of the EU ETS reform.

What sanctions apply under the CBAM?

The definitive phase of the CBAM has been running since 1 January 2026. Companies that import certain emission-intensive goods such as steel, aluminium, cement or fertilisers from non-EU countries need the status of authorised CBAM declarant and must buy and surrender CBAM certificates for the embedded emissions.

Relief from the Omnibus package: companies that import less than 50 tonnes of CBAM goods per year are exempt from the obligations. This does not apply to electricity and hydrogen.

The so-called “climate tariff” supplements the EU ETS and provides for the following sanctions:

  • Missing certificates: in accordance with the EU ETS, fines of EUR 100 per tonne of CO2 equivalent are imposed.
  • Anyone importing CBAM goods without the status of authorized declarant must expect even higher penalties.
  • In the event of violations, the authorised declarant status can be revoked. The company may then no longer import CBAM goods.
  • For the transitional phase (2023 to 2025), incomplete, incorrect or missing CBAM reports were subject to penalties of 10 to 50 euros per tonne of unreported emissions.


Read more:

Is your purchasing department ready for the ESG requirements?

Companies are now affected by a large number of sustainability requirements – and purchasing is no exception. Use our checklist to find out whether your purchasing organization is optimally prepared for ESG requirements.

When do EUDR sanctions apply?

Supply chain officers and buyers must prepare themselves for even more sanctions. If you place products on the EU internal market whose production has come at the expense of forests, you could face the following penalties under the EUDR:

  • Skimming off profits unlawfully made as a result of non-compliance with the EUDR
  • Fines in proportion to forest damage and value of goods, but at least 4 % of annual turnover
  • Seizure of goods or products
  • Temporary import bans
  • Exclusion from public funds and public tenders
  • Inclusion in a public list incl.
    Information on the violation

Also important: The EU has postponed the application of the EUDR once again. The obligations apply from 30 December 2026 for large and medium-sized companies and all traders, and from 30 June 2027 for micro and small enterprises. From then on, you may only place the relevant goods on the EU market if geolocation data and proof of origin are available. Keep this in mind today when ordering goods that will reach the EU single market from the end of December.

Read more:

What fines apply under the PPWR?

The EU Packaging and Packaging Waste Regulation (PPWR) has applied since 12 August 2026. In Germany, the Packaging Law Implementation Act (VerpackDG) governs how violations are penalised. It replaces the previous Packaging Act (VerpackG). Depending on the severity of the violation, companies face:

  • Fines of up to 200,000 euros, for example for placing packaging on the market without the required participation in a take-back system or for selling despite a distribution ban
  • Fines of up to 100,000 euros for breaches of registration, reporting and documentation obligations or of take-back and deposit obligations
  • Fines of up to 10,000 euros for certain formal violations
  • Distribution bans and public entries in the register

The PPWR introduces new sanctionable offences, such as missing declarations of conformity, missing technical documentation and breaches of the requirements on recyclability and recycled content. The European Commission recommends that authorities initially focus on warnings and corrective measures.

Read more:

What penalties apply for greenwashing under the EmpCo?

Since 27 September 2026, EmpCo has regulated misleading environmental claims and unlawful sustainability labels more strictly. In Germany, the requirements are implemented through the Act Against Unfair Competition. Violations may therefore primarily result in warnings, cease-and-desist claims, interim injunctions and legal action by competitors or associations.

In certain cases, fines may also apply. For widespread infringements, the fine can amount to up to EUR 50,000. For companies with annual revenue of more than EUR 1.25 million, the fine may amount to up to 4% of the affected EU annual revenue.

The European Commission halted the Green Claims Directive, which was intended to regulate environmental claims in addition, in June 2025. This makes EmpCo the relevant framework for environmental claims.

Read more:

What sanctions apply to the Digital Product Passport (DPP)?

With the Ecodesign for Sustainable Products Regulation (ESPR), the EU is gradually introducing the Digital Product Passport. It brings together information on a product’s materials, origin, reparability and environmental impact. Companies that fail to meet the requirements face sanctions. Member states set the level of fines, but the ESPR already provides for the following measures:

  • Fines
  • Withdrawal and recall of products
  • Import bans
  • Temporary exclusion from public procurement

The battery passport will be the first mandatory product passport from 18 February 2027. In Germany, incorrect or incomplete information can lead to fines of up to 10,000 euros. For other product groups such as textiles and furniture, the EU has yet to define the requirements.

Frequently asked questions about ESG sanctions

Which ESG regulations provide for sanctions?

Sanctions apply under the CSRD, the CSDDD, the German Supply Chain Due Diligence Act (LkSG), the Carbon Border Adjustment Mechanism (CBAM), the EU Deforestation Regulation (EUDR) and the EmpCo directive against greenwashing, among others. The type and amount of sanctions differ by regulation.

What is the highest possible fine?

The highest fines are set by the turnover-based regulations. Under the CSDDD, fines of up to 3% of global net turnover are possible; under the EUDR, the maximum is at least 4% of annual EU turnover. On top of that come consequences such as exclusion from public contracts or confiscation of goods.

Has the EU Omnibus package changed the sanctions?

Yes. The Omnibus I package weakened the CSDDD: it now only applies to companies with 5,000 or more employees and 1.5 billion euros in turnover, from 26 July 2029, with a maximum fine of 3% instead of 5% and without EU-wide harmonised civil liability. For the CSRD, the group of companies required to report was reduced, and the CBAM now has an exemption for imports below 50 tonnes per year.

Does the German Supply Chain Act still apply?

Yes. The due diligence obligations under the LkSG continue to apply. A reform is set to abolish the reporting obligation and limit fines to serious violations; in practice, BAFA has already suspended the reporting obligation. In the medium term, the national implementation of the CSDDD is to replace the LkSG.

Are mid-sized companies affected by ESG sanctions?

Directly, mainly through the CBAM, EUDR and EmpCo, because these rules are not tied to company size. The CSRD, CSDDD and LkSG usually affect mid-sized companies indirectly: large customers pass their obligations on to their suppliers through contracts and data requests.

Save money and nerves with VERSO

To ensure that companies do not approach the sustainable transformation too carelessly, the EU provides for “effective, proportionate and dissuasive” measures in any case.

In view of the possible sanctions, we are happy to believe this – and help you to correctly implement the guidelines and regulations that apply to you. Not only our top software, but also our experienced consultants and our specialized partners are at your side. Feel free to get in touch with us!

Subscribe to our newsletter!

Register now to arrange a free demo appointment and get to know our solutions at first hand.

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers

Get to know the software!

Update LkSG und CSDDD - die wichtigsten Änderungen
04.08.2026

CSDDD and LkSG Implementation: Why Companies Need Resilient Supplier Processes Now

What’s changing with LkSG and CSDDD, what the timeline for CSDDD implementation in Germany means, and why companies should integrate due diligence obligations into resilient supplier processes.

In brief

  • CSDDD implementation refers to transposing the European due diligence directive into national law
  • Affected companies must systematically identify, prioritize, and address human rights and environmental risks in their supply chains
  • In Germany, the CSDDD will replace the LkSG; it applies from July 26, 2029, for companies with 5,000 or more employees and €1.5 billion or more in revenue.

The rules around corporate due diligence obligations are in flux. CSDDD implementation was adjusted through the Omnibus package. As a result, the scope, individual requirements, and timeline have changed.

For many companies, one thought seems obvious: wait until it’s finally clear who has to meet which requirements and when.

But that reduces the European supply chain directive, the CSDDD, too much to thresholds and deadlines. The underlying task remains the same: companies must identify, prioritize, and appropriately address human rights and environmental risks in their supply chains. Directly affected companies need their own due diligence processes, and smaller companies and suppliers will continue to be drawn in through their customers’ data requests, evidence, and measures.

Waiting to build resilient structures doesn’t automatically buy time. Supplier data can’t be completed on short notice, responsibilities can’t be clarified overnight, and supplier relationships can’t be developed through a one-time questionnaire.

For efficient LkSG and CSDDD implementation, companies shouldn’t treat due diligence as an isolated compliance task. It makes more sense to embed it firmly into existing supplier and risk management.

What does CSDDD implementation mean?

CSDDD stands for Corporate Sustainability Due Diligence Directive. In German, it’s often referred to as the EU supply chain law or European supply chain directive.

The directive obligates the companies it covers to embed human rights and environmental due diligence into their own operations, subsidiaries, and relevant business relationships. The goal is to identify negative impacts on people and the environment and, where possible, prevent, mitigate, or end them.

Core due diligence obligations include, in particular:

  • integrating due diligence into policies and risk management systems,
  • identifying and prioritizing actual and potential negative impacts,
  • implementing prevention and remediation measures,
  • enabling complaint and grievance mechanisms,
  • monitoring the effectiveness of measures,
  • and documenting implementation in a traceable way.

The CSDDD therefore doesn’t describe a one-time review process. Due diligence forms a cycle: risks are identified, measures are decided, progress is reviewed, and processes are adjusted as needed.

A completed supplier questionnaire can provide information for a risk analysis. However, it replaces neither the prioritization of risks nor the tracking of measures nor continuous supply chain monitoring.

What are the differences and similarities between CSDDD and LkSG?

Germany’s Supply Chain Due Diligence Act, known as LkSG, has been in effect since 2023. It currently forms the German legal framework for human rights and certain environmental due diligence obligations in supply chains.

The CSDDD applies a similar underlying logic at the European level. It, too, requires systematic risk management, prevention and remediation measures, complaint mechanisms, and monitoring of effectiveness.

Criterion LkSG CSDDD
Legal level German law EU directive, to be transposed nationally
Applicable from Since 2023 July 26, 2029 (first wave)
Threshold Currently 1,000 employees (restructuring planned) 5,000 employees / €1.5 billion revenue
Core obligations Risk analysis, prevention/remediation, complaints, documentation Largely equivalent, risk-based approach

What do LkSG and CSDDD implementation have in common?

For companies in Germany, LkSG and CSDDD aren’t two entirely separate tasks. Existing structures from LkSG implementation can form an important foundation for CSDDD implementation. These include, for example:

  • defined responsibilites,
  • structured supplier and risk analyses,
  • prevention and remediation measures,
  • complaint procedures,
  • as well as documentation and effectiveness monitoring.

What changes with the CSDDD?

While the LkSG is a German law, the CSDDD creates a common European framework. It must be transposed into national law by member states, which will further develop Germany’s existing regulations.

Until national transposition takes place, the LkSG formally remains in effect, though enforcement has already become more restrained. Details on implementation status can be found in the timeline section.

What matters for you in procurement: don’t build a separate process for every new law — build one resilient system for corporate due diligence obligations.

When does the CSDDD apply? Germany’s implementation timeline

The CSDDD is already in force and was adjusted as part of the Omnibus package. The changes affect, among other things, the scope, individual due diligence obligations, and the timeline.

The following requirements remain particularly relevant for companies:

  • systematically identifying and prioritizing human rights and environmental risks,
  • implementing appropriate prevention and remediation measures,
  • providing a complaint mechanism,
  • monitoring the effectiveness of measures,
  • and documenting implementation in a traceable way.

In Germany, the amended CSDDD still needs to be transposed into national law. Until a corresponding new regulation is in place, the LkSG remains the existing legal framework. It’s expected, however, that Germany will implement the CSDDD largely in close alignment with the European requirements.

The direction in Germany is now clear: the federal government has decided to transpose the CSDDD into German law on a one-to-one basis. The LkSG will be restructured accordingly; its scope is set to be limited to companies with 5,000 or more employees and revenue exceeding €1.5 billion. The external LkSG reporting obligation is effectively already obsolete: BAFA has not reviewed it since fall 2025, and its formal repeal is underway.

For preparation purposes, waiting for every regulatory detail makes little sense. The operational fundamentals are already clear: companies need resilient supplier data, a risk-based approach, documented measures, and clear responsibilities.

Companies that wait to build these structures until after the legislative process concludes will then be starting with the most time-intensive tasks.

Which companies are affected by the EU supply chain law?

Following the adjustments made through the Omnibus package, the so-called EU supply chain law, the CSDDD, applies from July 2029 to companies with more than 5,000 employees and worldwide net revenue exceeding €1.5 billion. This covers both companies headquartered in the EU and certain companies from non-EU countries, provided they meet the relevant revenue criteria in the European single market.

In practice, however, direct legal applicability isn’t the only factor that matters. Smaller companies and suppliers can also have requirements passed on to them through their business relationships. This makes it worth distinguishing between direct and indirect applicability.

Which companies are directly affected by the CSDDD?

Directly affected companies must integrate the statutory due diligence obligations into their organization and risk management. These include, among others:

  • identifying risks and negative impacts,
  • prioritizing them,
  • implementing prevention and remediation measures,
  • providing complaint mechanisms,
  • monitoring the effectiveness of measures,
  • and documenting implementation.

These tasks can’t be handled by legal, compliance, or sustainability teams alone. They directly affect procurement, supplier, and risk processes.

Are mid-market companies affected by the CSDDD?

Mid-market companies generally don’t fall directly within the CSDDD’s scope. Even so, they can be affected through their business relationships.

Large customers need information to assess their own risks and meet their due diligence obligations. As a result, they may request from suppliers, for example:

  • information on production sites and supply chains,
  • evidence of human rights or environmental standards,
  • self-disclosures and risk information,
  • contractual assurances,
  • and participation in prevention or improvement measures.

This doesn’t create automatic legal equivalence with directly affected companies. In practice, however, requirements are passed down through the supply chain. Not being directly affected doesn’t automatically mean there’s no need to act.

Want a quick overview of the CSDDD?

Our CSDDD factsheet, including a comparison with the LkSG, gives you all the key information on the supply chain law in one compact summary.

What does CSDDD implementation mean for procurement and supplier management?

Responsibility for the CSDDD sits at the company level. For operational implementation, though, procurement plays a central role: this is where suppliers are selected and assessed, requirements are communicated, and measures are carried out within the business relationship.

A resilient data foundation comes first. Companies need to know which suppliers and production sites they work with, and which countries, industries, or activities may carry elevated risks. Often, however, this information is scattered across ERP systems, spreadsheets, emails, and various departments.

The task, therefore, isn’t just about collecting more data. Information needs to be current, plausible, and clearly assigned to a supplier or site. Only then can companies meaningfully assess and prioritize risks.

Why supplier questionnaires aren’t enough for CSDDD implementation

One-time supplier questionnaires only capture a snapshot. Production conditions, sites, and risk situations can change, evidence can become outdated, and new information can emerge. Completeness and quality of responses also often vary considerably.

Above all, the due diligence process doesn’t end with data collection. When risks are identified, companies must initiate appropriate prevention or remediation measures, assign responsibilities, and review effectiveness.

For procurement, this means in particular:

  • bringing supplier and risk data together in a usable way,
  • continuously assessing and prioritizing risks,
  • clearly communicating requirements and evidence needed,
  • tracking measures and deadlines,
  • and documenting decisions and supplier communication in a traceable way.

Supplier management shouldn’t be reduced to control, though. Smaller suppliers in particular may not yet have the systems or resources to meet every requirement immediately. Effective due diligence therefore pairs clear expectations with targeted supplier development.

How are companies preparing for CSDDD implementation?

The CSDDD’s core requirements are set. Companies should now align their existing supplier and risk processes to systematically capture risks, track measures, and document implementation in a traceable way.

Five areas are especially important here:

1. Clarify responsibilities

Procurement, sustainability, compliance, legal, and management need to be clearly aligned. Companies should define who assesses risks, requests information, decides on measures, escalates critical cases, and documents effectiveness.

2. Bring supplier and risk data together

Much of the relevant information already exists — supplier master data, audit reports, certificates, or quality assessments, for example. What’s often missing is a shared view. Companies should therefore check what data exists, how current it is, and where gaps remain.

3. Establish continuous risk management

Risk assessments should be updated regularly and whenever specific triggers arise. New suppliers, changed production sites, incidents, or complaints can all call for a renewed assessment. A risk-based approach helps focus limited resources on the most important cases.

4. Document measures and evidence centrally

Risk analyses, supplier communication, evidence, measures, deadlines, and effectiveness checks should be documented in one shared process. This keeps companies audit-ready and avoids time-consuming reconstruction from emails and spreadsheets.

5. Automate recurring processes

Requests, reminders, deadlines, and monitoring are difficult to manage manually on an ongoing basis for large supplier bases. Automation reduces the burden of recurring tasks and creates a consistent documentation history.

Companies shouldn’t build a separate structure just for the CSDDD. A more sustainable approach is supplier management that can accommodate different due diligence obligations, customer requirements, and other regulatory requirements (EUDR, PPWR, CBAM, etc.).

Go deeper on due diligence obligations

Find out how to ensure due diligence, such as under the CSDDD, efficiently and in compliance with the law in our whitepaper on supply chain due diligence obligations.

Software for LkSG and CSDDD implementation

Efficient implementation requires connecting supplier data, risk analyses, requests, measures, and evidence.

VERSO Supply Chain Hub helps companies map these tasks into one central process. You can:

  • bring supplier and risk data together in a structured way,
  • assess and prioritize suppliers based on relevant risks,
  • automate requests and reminders,
  • continuously monitor risks,
  • manage prevention and remediation measures,
  • track responsibilities and deadlines,
  • and centrally document evidence and supplier communication.

This doesn’t create an additional standalone solution for the CSDDD. Requirements are embedded where supplier relationships are already managed.

Assess CSDDD requirements and implement them efficiently with us

Want to know which requirements are relevant for your company and how to integrate them into existing supplier processes?

In a no-obligation conversation, we’ll show you how VERSO Supply Chain Hub supports you with LkSG and CSDDD implementation.

Frequently asked questions about LkSG and CSDDD

What does CSDDD stand for?

CSDDD stands for Corporate Sustainability Due Diligence Directive. The EU directive is often referred to as the EU supply chain law and governs human rights and environmental due diligence obligations for large companies.

What is the CSDDD, simply explained?

The CSDDD requires affected companies to systematically identify and prioritize risks to people and the environment across their operations and business relationships. This must be followed by appropriate prevention or remediation measures and regular effectiveness checks.

What’s the difference between CSDDD and LkSG?

The LkSG is an already applicable German law. The CSDDD creates a common European framework that member states transpose into national law. Both regimes require, among other things, risk management, prevention and remediation measures, complaint procedures, and documentation.

Is the CSDDD already in force?

Yes. The CSDDD entered into force on July 25, 2024, and its scope was significantly reduced through the Omnibus package (Directive (EU) 2026/470, finalized March 18, 2026). Member states must transpose it into national law by July 26, 2028; the obligations apply uniformly to affected companies from July 26, 2029.

When do I need to implement the CSDDD?

Application starts July 26, 2029, for the largest companies. Germany has also decided on a one-to-one transposition of the CSDDD, combined with a restructuring of the LkSG. That doesn’t mean you should wait until then, though: since you’ll need a lot of information from your supply chain, you should start preparing your data foundation and processes well before that.

What changes for mid-market suppliers?

Mid-market companies generally aren’t directly covered by the CSDDD. They can, however, be indirectly affected when larger customers request information, evidence, contractual assurances, or improvement measures to meet their own due diligence obligations.

How do mid-market suppliers meet the requirements?

As a supplier, you demonstrate due diligence through self-disclosures on human rights and environmental risks within your own operations. This is supplemented by concrete evidence such as certificates, audit reports, or questionnaires that your customers may request. When risks are identified, this often leads to involvement in the customer’s prevention or remediation measures. Ideally, your customers set clear expectations and support you with targeted supplier development.

Which industries does the CSDDD affect?

The CSDDD applies across industries in principle. The specific need for action, however, depends heavily on supply chain structure, production countries, raw materials used, and the human rights and environmental risk profile.

What data do I need for CSDDD implementation?

You fundamentally need resilient supplier and site data. You’ll also need risk indicators by country or industry, evidence, and the status of measures on hand.

What does due diligence mean in the context of the CSDDD?

Due diligence means systematically identifying, prioritizing, and appropriately addressing risks and negative impacts on people and the environment. Companies must also enable complaints, monitor measures, and document implementation in a traceable way.

What does the CSDDD require for risk management?

Companies must systematically identify actual and potential negative impacts and prioritize them by severity and likelihood. Based on this, suitable measures must be defined, reviewed regularly, and adjusted as needed.

What complaint mechanisms does the CSDDD require?

Companies must establish appropriate procedures through which affected individuals, employee representatives, or relevant organizations can submit reports and complaints. These reports must be reviewed, handled, and factored into risk management in a structured way.

What happens in the event of CSDDD violations?

Violations can result in regulatory action and financial penalties. Companies also face liability, reputational, and business risks — for example, if customer requirements aren’t met or supply chain risks aren’t adequately addressed.

What changes does the CSDDD Omnibus bring?

The Omnibus package adjusted the CSDDD’s scope, individual requirements, and timeline. The core obligation remains, though: affected companies must establish a risk-based process for identifying, addressing, and monitoring human rights and environmental impacts.

What criticism has the CSDDD faced?

Critics point mainly to added administrative burden, high implementation costs, and indirect strain on smaller suppliers. Supporters, on the other hand, expect more consistent European standards, greater transparency, better protection for people and the environment, and more systematic risk management.

Which tools support CSDDD implementation?

Suitable CSDDD software connects supplier data, risk analysis, continuous monitoring, and measure management. Automated requests and reminders are also important, along with central documentation of evidence, deadlines, and supplier communication.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up to receive regular updates on:

Current ESG topics and regulatory changes
Best practices in ESG and sustainable supply chains
VERSO news
Sustainability events, and more

Worker welding a steel pipe – illustrating CBAM's impact on steel imports into the EU
30.01.2026

Fit for CBAM: Key Facts and Requirements

As part of the EU’s climate strategy, the Carbon Border Adjustment Mechanism (CBAM) puts a price on CO2 emissions from goods imported into the EU from non-EU countries. The goal is to promote emission reductions and protect the competitiveness of EU industry. This article outlines what companies need to know to ensure CBAM compliance.

What is CBAM? A brief overview

CBAM (Carbon Border Adjustment Mechanism) is the official name of EU Regulation 2023/956. It entered into force on 1 October 2023 and complements the EU Emissions Trading System (EU ETS). Together, they aim to reduce emissions from both goods produced within and imported into the EU.

Objectives of CBAM:

  • Strengthen existing emission reduction measures
  • Encourage companies to reduce emissions rather than relocate production
  • Protect EU-based companies from cost-related competitive disadvantages

Annex I of the CBAM regulation lists the relevant CN codes in detail.

The EU plans to expand the scope of CBAM. By 2030, all products covered under the EU ETS are expected to be included.

Overview of goods covered by CBAM: steel, aluminium, cement, fertilisers, electricity and hydrogen

CBAM reporting and certificates: deadlines and to-dos

Transitional phase 2023–2025: quarterly reports (“reporting obligation”)

Reports must be submitted within one month after the end of each quarter and include:

  • Company master data
  • CBAM account number
  • Quantity and type of imported goods
  • CBAM-relevant greenhouse gas emissions
    • Specific emissions, not default values
    • Direct and indirect emissions (in line with the CBAM scope during the transitional phase)
  • CO2 price paid in the country of origin

From 2026: annual CBAM declaration – certificates from 2027

Starting 1 January 2026:

From January 1, 2026, emissions from imported CBAM goods will be recorded for the first time for later financial settlement. The actual compensation through CBAM certificates, however, will only take place from 2027 as part of the annual CBAM declaration. A prerequisite is registration as an authorized CBAM declarant, as only authorized declarants are permitted to import CBAM goods from 2026 onward.

From 2027, CBAM certificates can be purchased via a central platform. The price of CBAM certificates is based on the weekly average price of EU ETS certificates.

From the start of the certificate obligation in 2027, a sufficient number of CBAM certificates must be held at all times to cover at least 80 percent of imported CBAM goods. Companies are responsible for calculating the required compensation and corresponding number of certificates themselves. The CBAM module in the VERSO Supply Chain Hub supports this process.

Important: From 2026, only authorized declarants are allowed to import CBAM goods and purchase certificates.

From 2027: first annual CBAM declaration:

From 2027, the CBAM quarterly report will be replaced by the annual CBAM declaration.

    • To be submitted by September 30 of the following year
      (example: the CBAM declaration for 2026 is due on September 30, 2027)
    • Total quantity of imported goods
    • Total amount of embedded emissions for each product group
    • Total number of CBAM certificates allocated to embedded emissions, minus any CO₂ price paid in the country of origin
CBAM timeline 2023–2027: key milestones from regulation entry into force to certificate trading obligation

CBAM FAQ

Answers to the most common questions about CBAM: what it means for your business and how to stay compliant.

Where do I submit CBAM reports?

Reports were submitted via the CBAM transitional registry until end of 2025, which you should be able to access via your national customs portal. From 2026 onward, the annual CBAM declaration will be submitted via the central CBAM Registry by authorized declarants.

Are there penalties for non-compliance with CBAM?

Yes. The regulation allows for proportionate and dissuasive penalties. Even during the transition phase, fines between 10 and 50 euros per tonne of unreported CO2 emissions may apply. From the start of the regular CBAM phase, sanctions may also apply in cases of missing registration, incorrect declarations, or failure to surrender CBAM certificates.

Are there thresholds for CBAM reporting?

Yes. If a company exceeds the threshold of 50 tonnes per year, the full CBAM obligations apply.

Can I still use default values in the report?

From 31 July 2024, default values may no longer be used. If you do not yet have real emissions data (e.g. from suppliers), Germany’s Emissions Trading Authority may still allow temporary use of default values if:
– You document your approach to obtaining real data
– You demonstrate that you made reasonable efforts to collect the data
– You provide your explanation in the “Comments” field of the transitional registry
– Your submitted report must be internally consistent – review it carefully.

Will the Omnibus proposal change anything?

Adjustments to the CBAM implementation timeline and design were introduced as part of the Omnibus package:
Deferred payment obligation: 2026 is the first emissions year, but CBAM certificates must only be purchased and surrendered from 2027 onward.
New reporting logic: Quarterly reporting ends in 2025 and is replaced by an annual CBAM declaration from 2026 onward (deadline: September 30).
New threshold: The €150 threshold is removed; instead, a quantity threshold of 50 tonnes per year applies.
Central registration: From 2026 onward, only authorized CBAM declarants may import CBAM goods.

Tips for CBAM implementation

CBAM compliance adds administrative effort – particularly around data collection. Close collaboration with suppliers is crucial.

Solutions like the our CBAM Tool can support companies by automating data capture, monitoring emissions, managing certificates, and ensuring documentation.

Background knowledge on CBAM

In 2005, the EU ETS was introduced as the EU’s instrument to meet Kyoto Protocol targets. It has undergone multiple reforms – most recently in 2021 as part of the Fit-for-55 package.

The ETS operates as a cap-and-trade system: companies receive an emissions allowance and must buy more if they exceed it.

This created a challenge: to avoid EU regulations and costs, some companies moved their CO2-intensive production to countries with lower or no carbon pricing – a practice known as “carbon leakage”.

*This information is summarized editorial content and should not be considered legal advice. VERSO assumes no liability. 

LKW-Fahrer mit Klemmbrett – Symbolbild für die Dekarbonisierung der Lieferkette
02.12.2025

Supply Chain Decarbonization: How To Achieve Your Climate Goals

Engage suppliers and strategically reduce supply chain emissions – your step-by-step guide to supply chain decarbonization.

Around 80% of a company’s emissions originate in the supply chain, making it a key focus on the path to net zero. But setting climate targets alone isn’t enough. The real challenge is achieving them. This article explores how to make supply chain decarbonization a reality – by turning targets into actions.

Why is it so important to decarbonize your supply chain?

Let’s look at two key reasons why decarbonizing the supply chain should be a top priority for businesses.

Climate action is no longer optional

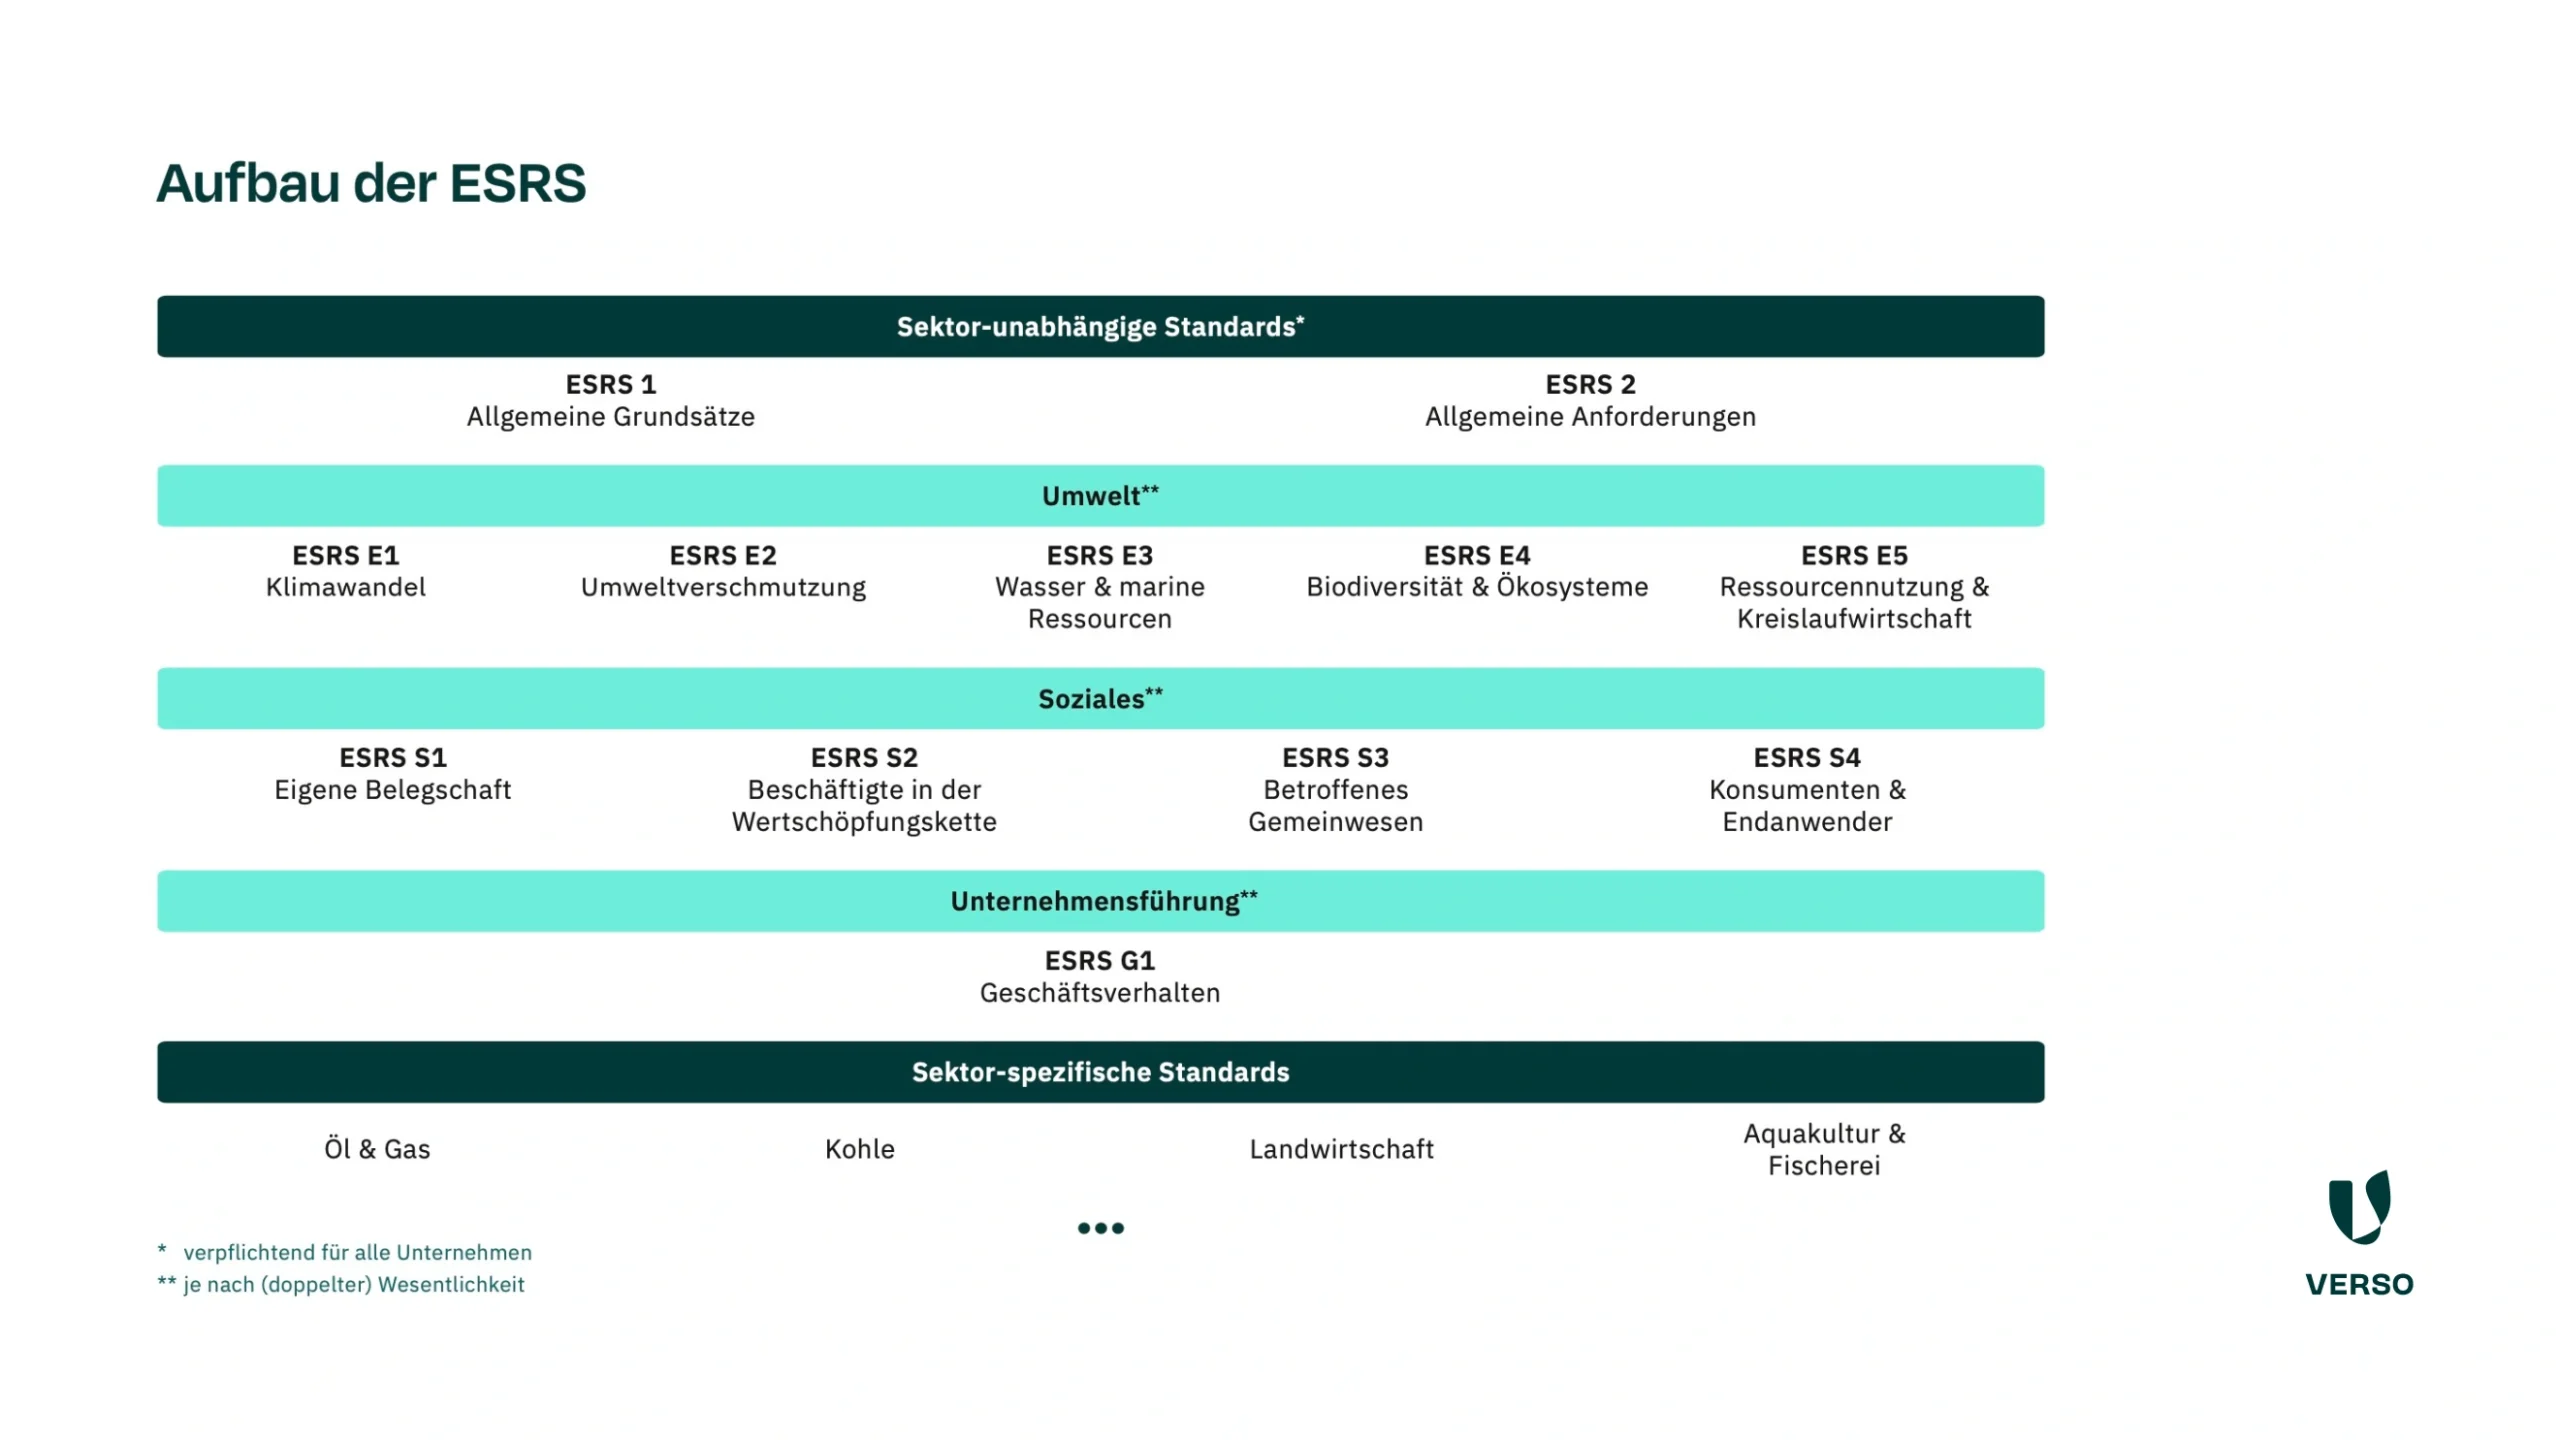
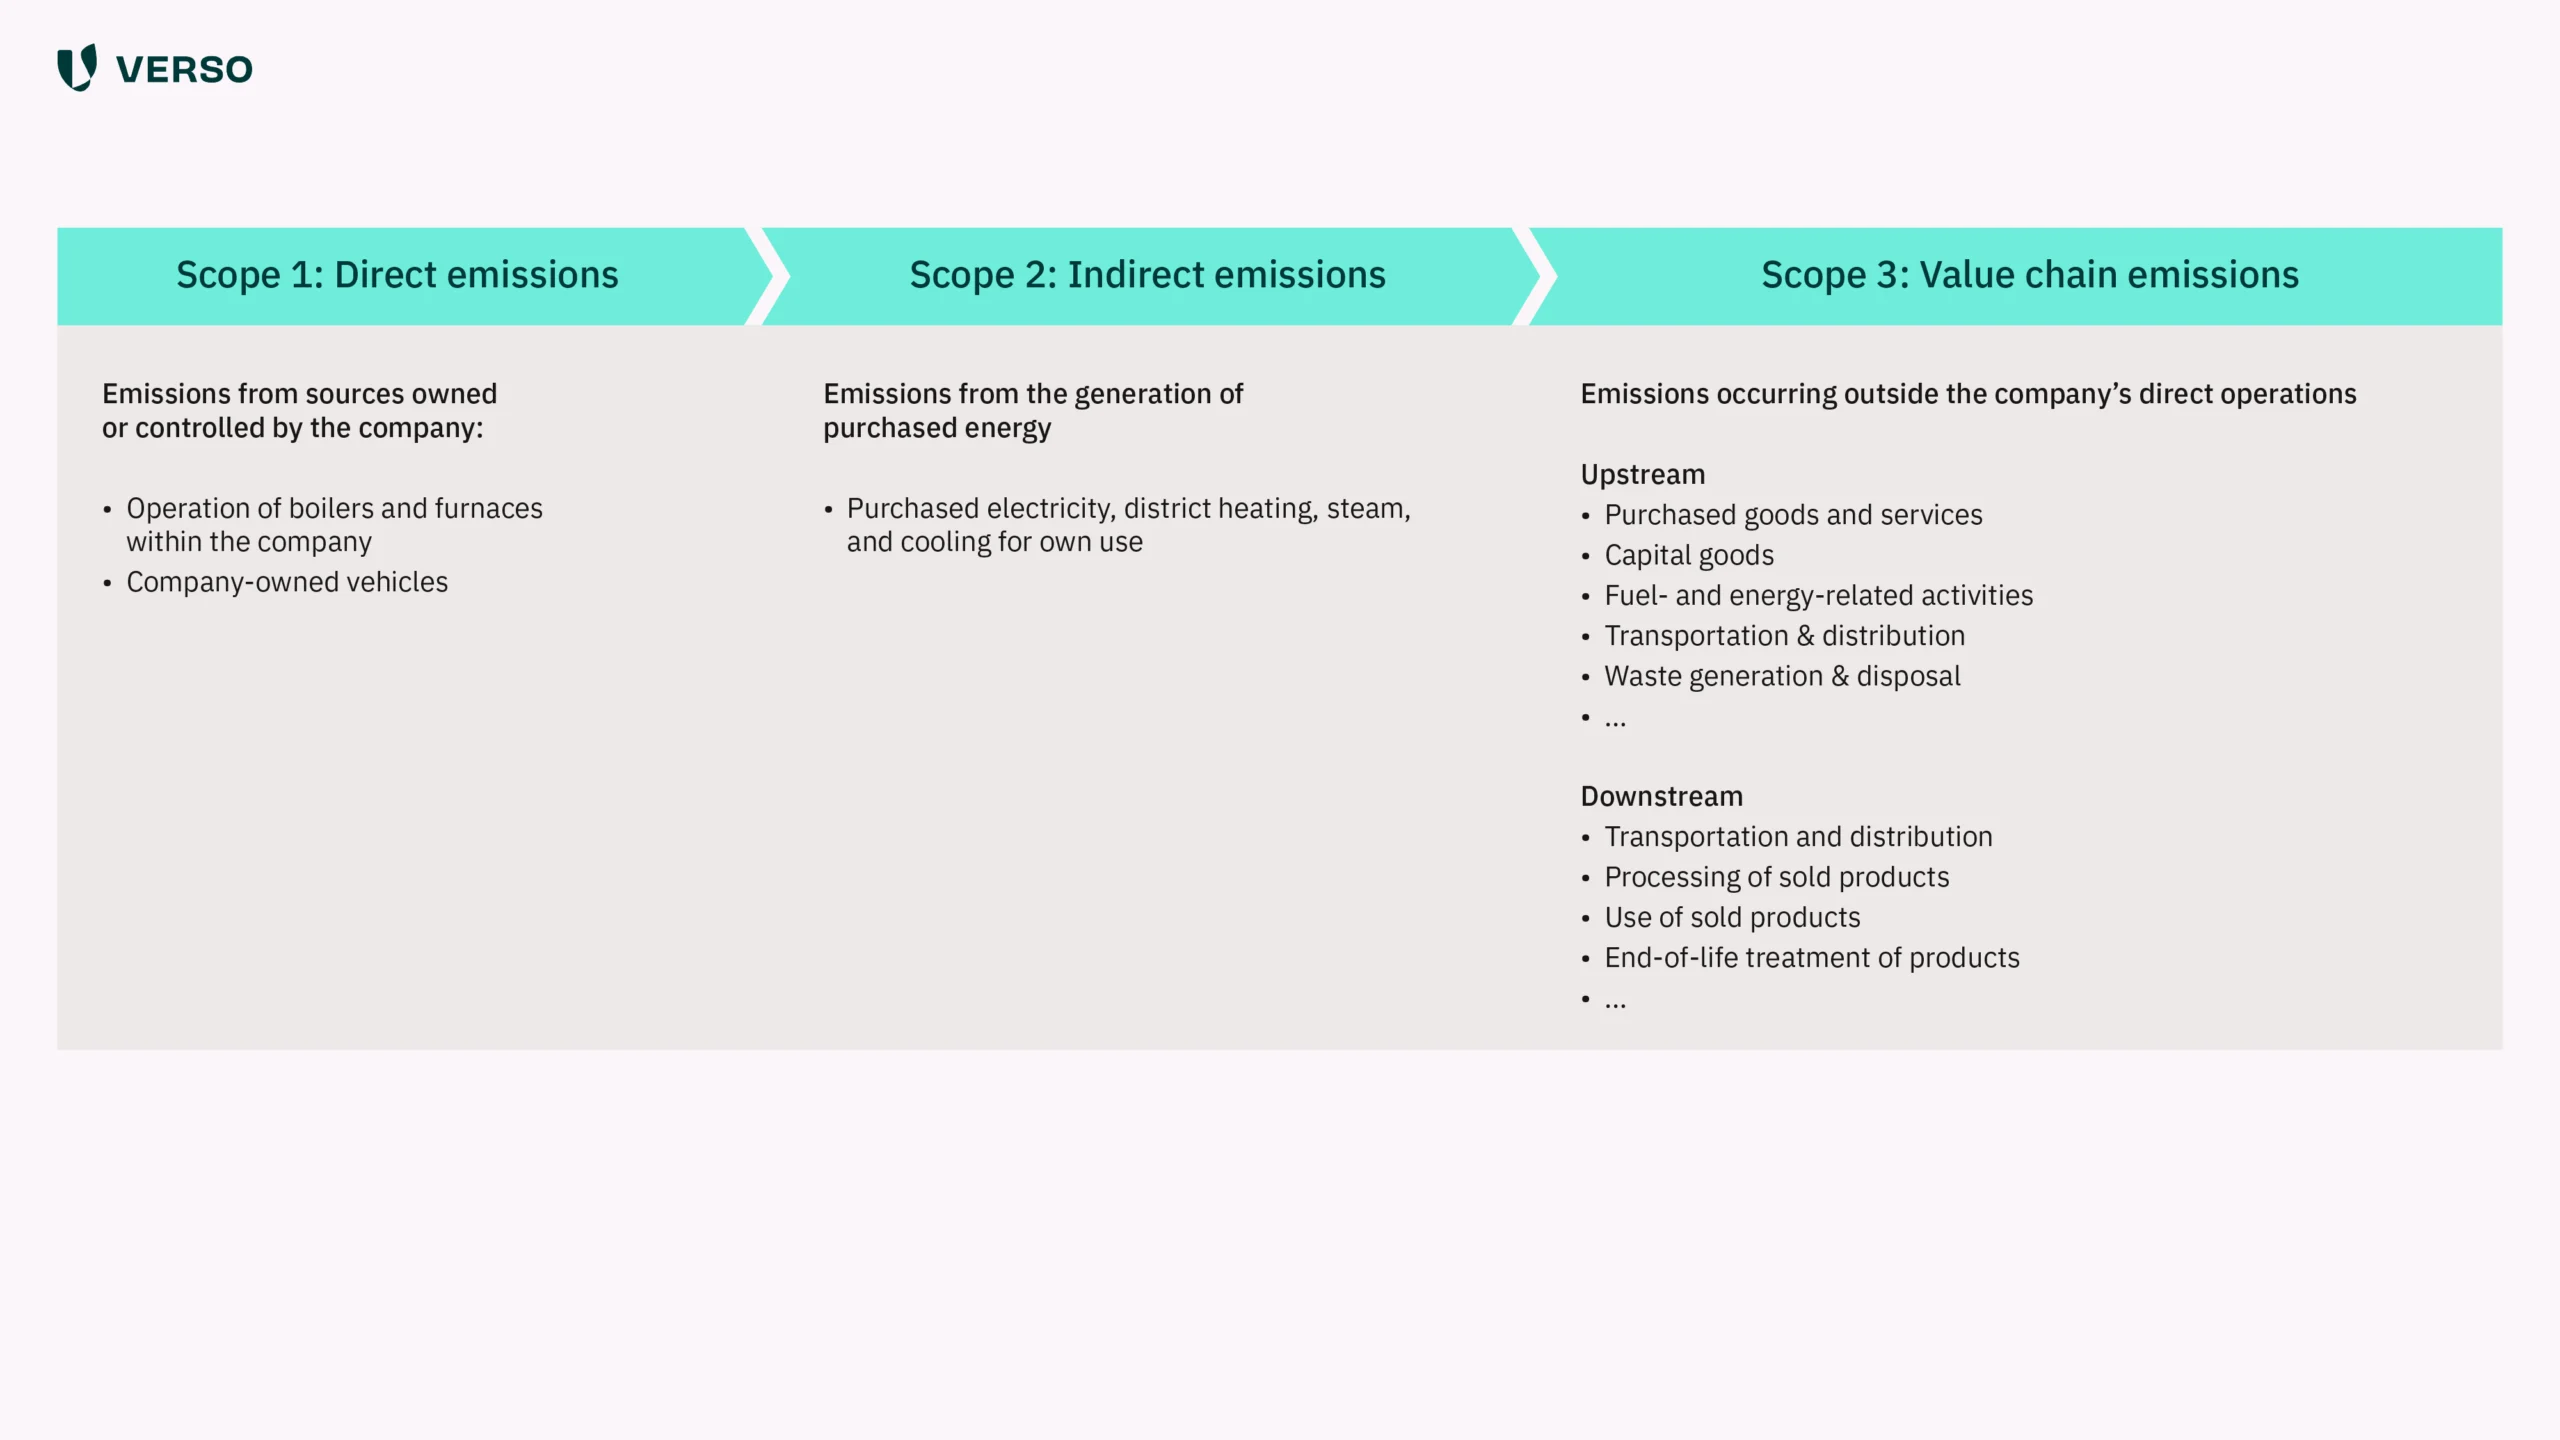
Regulations such as CSDDD, EUDR, and CBAM demand greater supply chain transparency, while CSRD’s ESRS E1 standard (Climate Change and Climate Protection) requires companies to set and track emission reduction targets – including Scope 3.

Overview on Scopes 1-3

That’s the compliance side. But focusing only on regulations means dealing with bureaucracy without unlocking real business value.

Supply chain decarbonization duture-proofs your business

Even if your company isn’t legally required to take climate action, proactively reducing emissions pays off.

Three Reasons to act now: 

  1. Climate risks disrupt supply chains. Extreme weather events are becoming more frequent, damaging factories, transport routes, and infrastructure. The result? Delays, shortages, and financial losses.
  2. Sustainable products drive competitive advantage. A Capgemini study found that 79% of consumers want to make more sustainable purchasing choices, and 66% actively look for eco-friendly products and services.
  3. ESG commitments are now a key factor in procurement. Large corporations subject to CSRD or CSDDD will require clear ESG data from suppliers. According to the Business Development Bank of Canada, 92% of large companies will demand ESG disclosures from their vendors.

How to assess and decarbonize your supply chain 

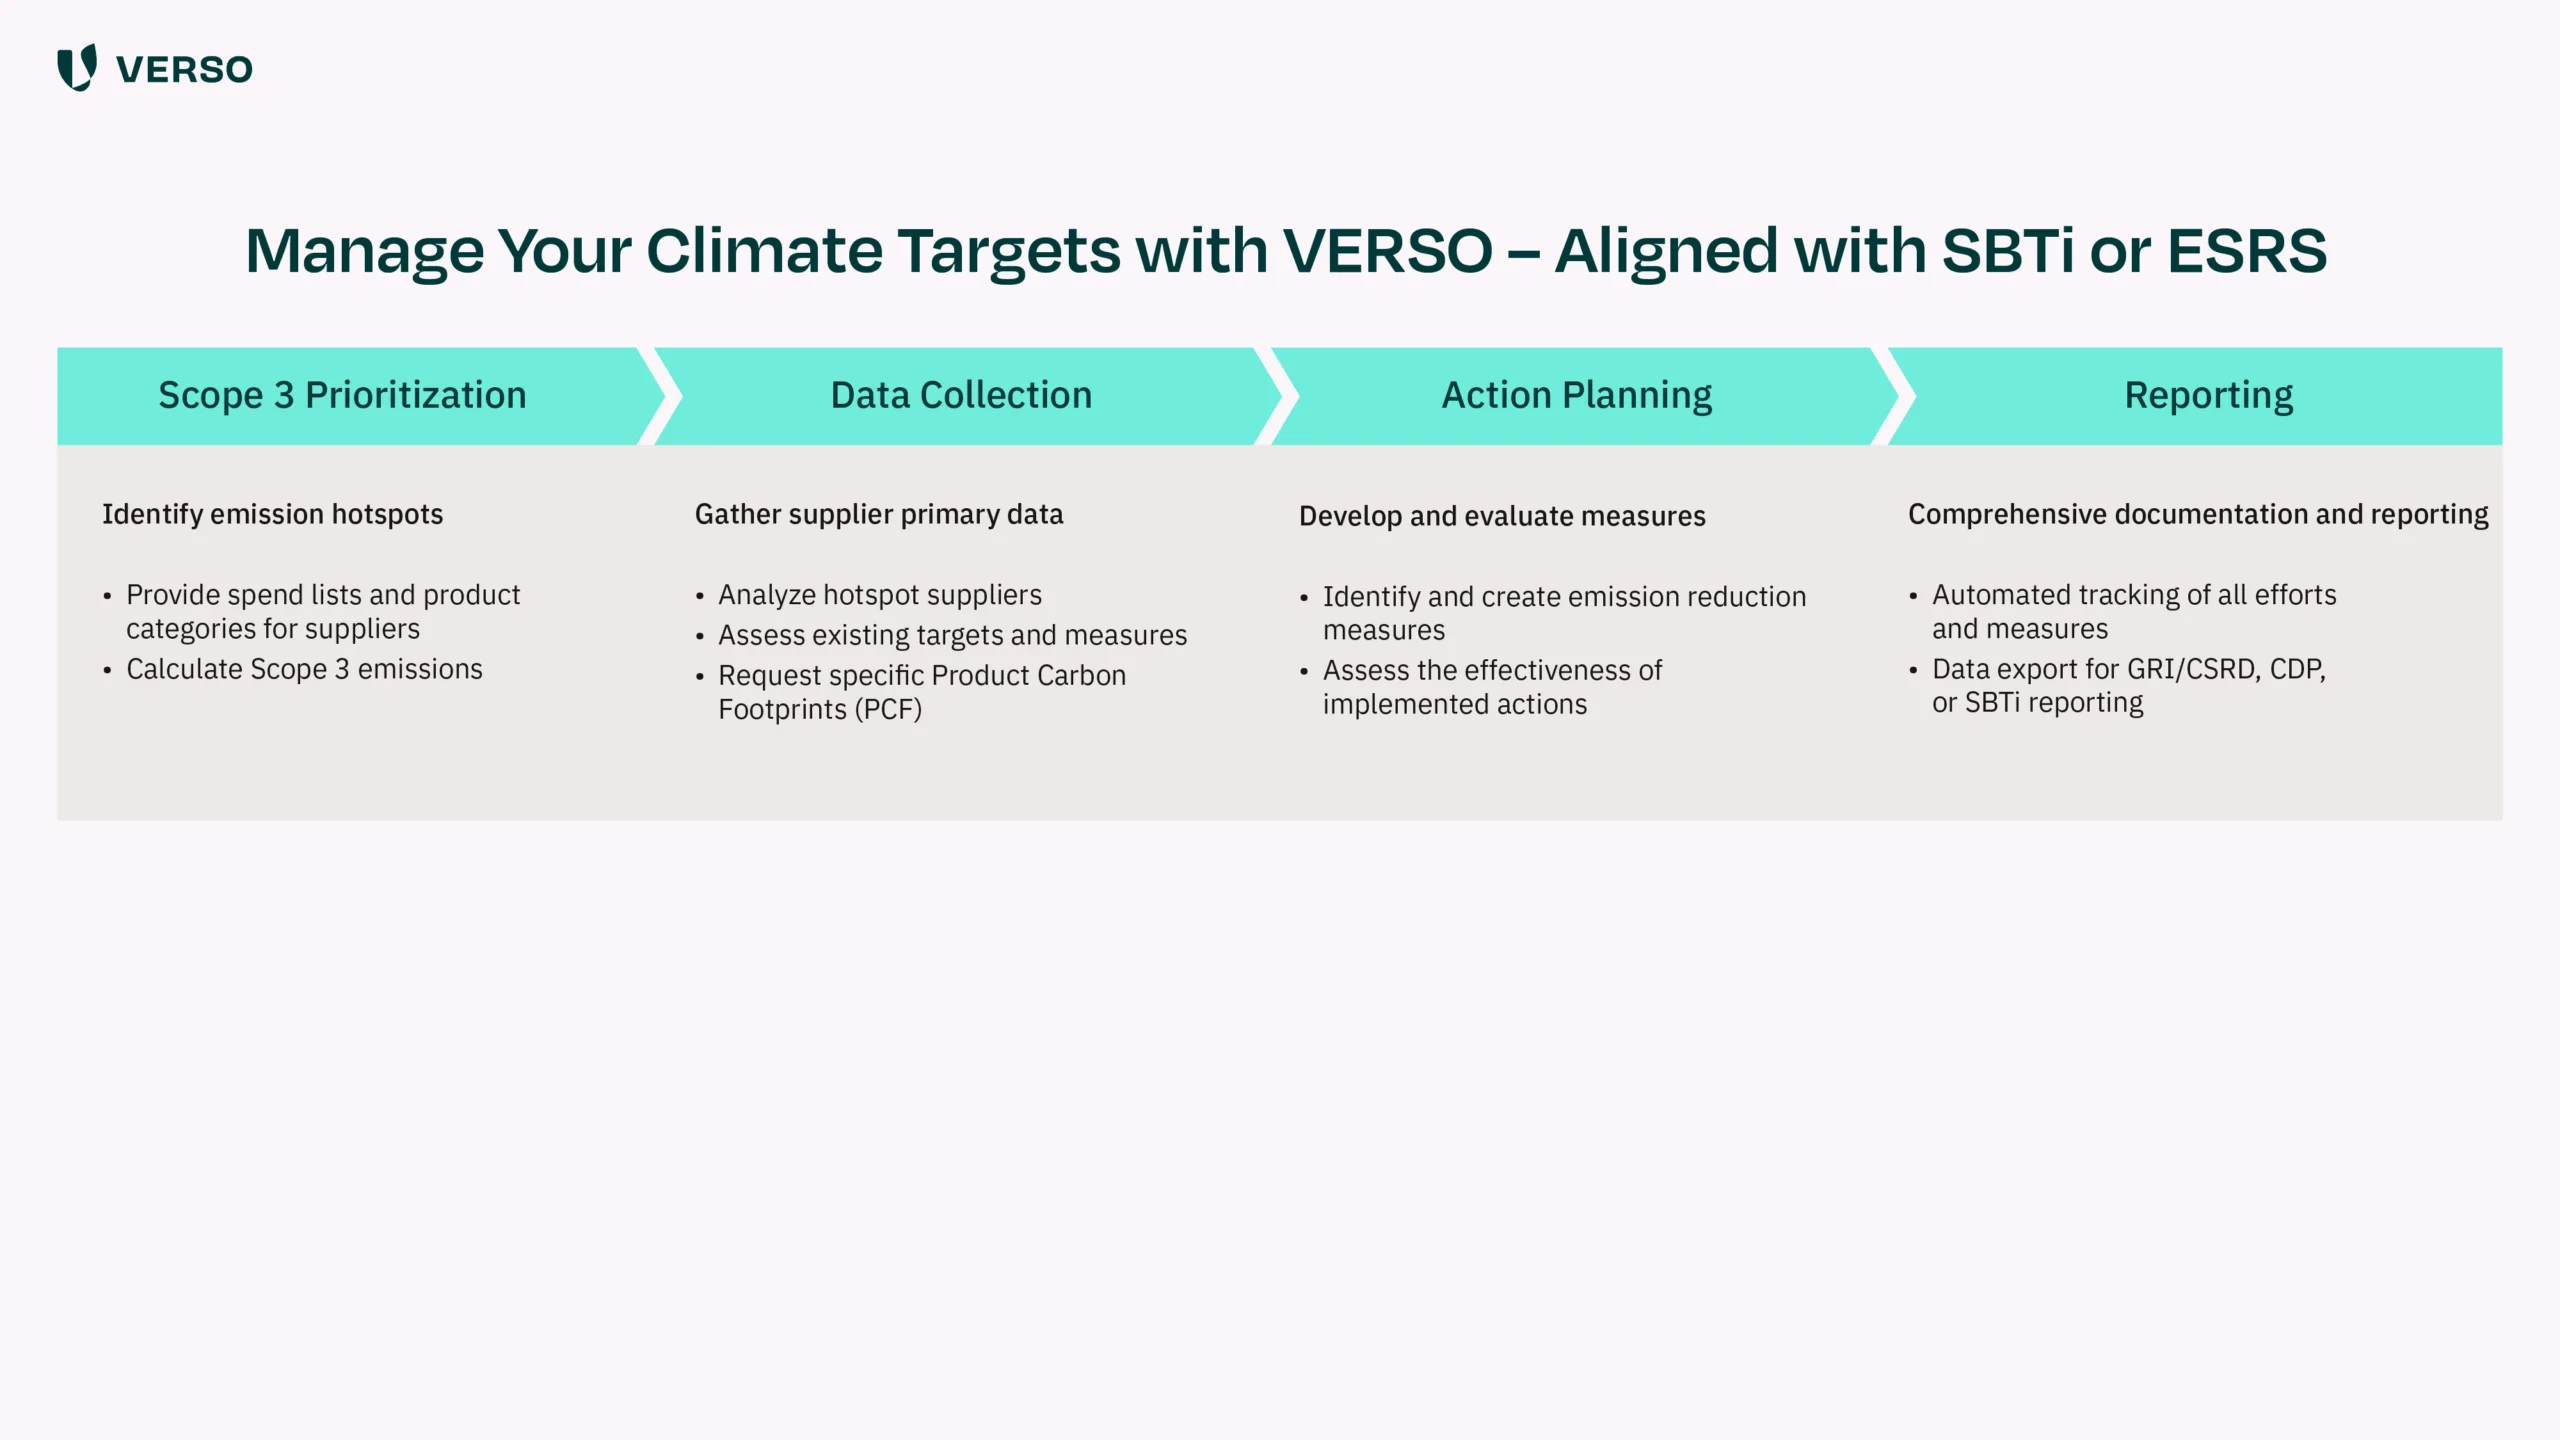
Step 1: Estimate scope 3 emissions

Start by mapping out your supplier network and compiling a spend list and product categories. This helps you estimate emissions across your supply chain.

If precise data is unavailable, start with industry benchmarks and refine your estimates as supplier-specific data becomes available.

Step 2: Identify hotspots & assess supplier climate maturity

Next, evaluate which suppliers contribute the most emissions and how advanced their climate strategies are. The VERSO Supply Chain Hub automates this assessment.

Supplier climate maturity levels: 

  • No climate strategy: No decarbonization measures in place. 
  • Low maturity: Some CO₂ reduction efforts, but no structured plan. 
  • Intermediate maturity: Concrete reduction measures exist but aren’t fully embedded in business operations. 
  • High maturity: Decarbonization is systematically integrated into corporate strategy. 
  • Best practice leader: Sustainability has long been a priority, with innovative approaches and industry-leading standards.

Key assessment indicators: 

  • Raw material sourcing
  • Energy & resource efficiency
  • Use of renewable energy in production & transport
  • Verified CO₂ offset projects
  • Voluntary sustainability reporting

By identifying emission hotspots and assessing supplier maturity, you can prioritize action where it’s needed most.

Step 3: Set climate targets & engage suppliers 

Define science-based climate targets aligned with the Paris Agreement and backed by climate research. The Science Based Targets initiative (SBTi) offers industry-specific guidance.

Once goals are set, it’s time to engage your suppliers. The SBTi recommends a five-step approach: 

  1. Communicate climate expectations to suppliers. 
  2. Collaborate to align on shared goals. 
  3. Support suppliers with knowledge and resources. 
  4. Monitor progress through transparent data tracking. 
  5. Scale and refine strategies over time. 

Pro tip: Involve suppliers from the start to foster collaboration. Decarbonization is a team effort! 

Step 4: Implement & scale your climate strategy

To reach long-term supply chain climate goals, companies must actively support their suppliers in implementing sustainable practices. 

Ways to drive climate progress in your supply chain: 

  • Provide knowledge & resources: Trainings and tools can improve supplier climate maturity.
  • Create competitive pressure: Large corporations increasingly demand ESG data, and reporting requirements will expand significantly in the coming years.

Regularly review progress, optimize processes, and keep climate action on the agenda in supplier meetings.

Transparency and accountability are key. Make it clear to your suppliers: Those who don’t commit to sustainability may risk losing business.

That said, low-maturity suppliers won’t transform overnight. But they should demonstrate intent to shift toward sustainable production and logistics. In the long run, climate action strengthens not only the environment but also supply chain resilience.

How to make supply chain decarbonization easier

The larger and more complex your supply chain, the harder it is to track emissions and manage climate action. Fragmented data and limited resources create major challenges for procurement teams.

So, how can you achieve your supply chain climate goals efficiently? 

With the right tools! The VERSO Climate Hub and VERSO Supply Chain Hub simplify supply chain decarbonization:

  • VERSO Supply Chain Hub automates supplier climate maturity assessments and collects supplier-specific CO₂ footprints. These insights feed into the Climate Hub, refining your strategy and tracking reductions.
  • Built-in reporting tools generate compliant reports for GRI/CSRD, CDP, and SBTi.
Manage your Supply Chai Emissions with VERSO

Get in touch with us. Together, we’ll find the right strategy to help your company reach its net zero goals!

* This information is summarized editorial content and should not be considered legal advice. VERSO assumes no liability. 

Baumstamm mit Efeublättern als Symbolbild für die EUDR
04.04.2025

EUDR: Key Questions and Answers

With the EUDR Regulation, the EU aims to strictly regulate trade in products that contribute to deforestation. But what does this mean in practice for affected companies, and how can they prepare for it? In this article, you’ll find answers to the most important questions about the new deforestation regulation, as well as practical tips for implementation.

What is the EUDR? A brief overview to the EU Deforestation Regulation

The EUDR introduces extensive due diligence obligations. Companies must ensure their products are deforestation-free. The focus is on transparency and traceability throughout the supply chain — businesses must be able to track a product’s journey from origin to market without gaps.

The EUDR requires companies to collect detailed data. As Klaus Wiesen, our supply chain expert, explains: “Given the complexity, it’s clear that software is a must for implementation. That already applies to the LkSG, but even more so for the EUDR — a pragmatic approach is nearly impossible without digital tools.”

When will the EUDR come into force?

Starting December 30, 2026, the EUDR enters its application phase for large and medium-sized companies. Small companies have until June 30, 2027 to implement the regulation.

Starting December 30, 2026 Starting June 30, 2027
Large and medium-sized companies meeting at least two of these criteria:

– More than 50 employees

– More than €10 million revenue

– More than €5 million balance sheet total

Small and micro-enterprises meeting at least two of these criteria:

– Fewer than 50 employees

– Less than €10 million revenue

– Less than €5 million balance sheet total


Overview on EUDR Deadlines

Who is affected by the EUDR (EU Deforestation Regulation)?

The EUDR is product-based and applies to all companies trading EUDR-relevant commodities and products derived from them.

The regulation differentiates between roles within the market, which determines specific obligations — see Determine your EUDR market role below.

First placer on the market Downstream operator
Companies placing EUDR-relevant products on or exporting from the EU market for the first time. Companies that further process or resell EUDR-relevant products for which the due diligence obligation has already been fulfilled in the upstream supply chain.

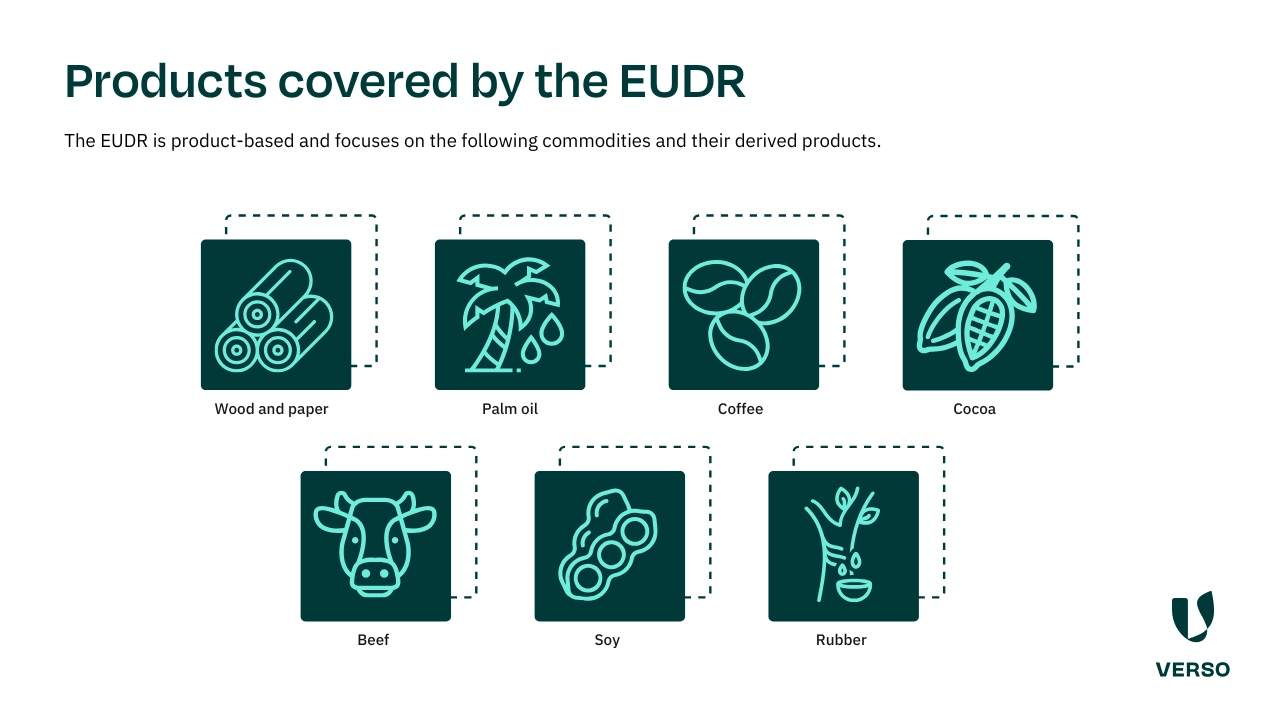
Which products are covered by the EUDR regulation?

The regulation applies to the following commodities and their derived products:

  • Wood
  • Palm oil
  • Coffee
  • Cocoa
  • Cattle
  • Soy
  • Rubber

There are no thresholds or volume limits. The list of covered commodities is expected to expand over time.

The EUDR Regulation provides for exceptions in the following cases:

  • 100% recycled materials
  • Packaging materials solely used for support, protection, or transportation
  • User manuals
  • Bamboo products
  • Products manufactured before the EUDR’s reference date (June 29, 2023), except for wood products
Overview on products covered by the EUDR

What conditions must products fulfill under the EU Deforestation Regulation?

Starting with the implementation phase: Import, trade and export of the above-mentioned raw materials and their derived products on the EU internal market are only permitted, if these three conditions are met:

  • Deforestation-free: The products were manufactured without converting natural forest into agricultural land or tree plantations after 31.12.2020. This also applies if deforestation was considered legal in the country of origin!
  • Production in accordance with the relevant rights of the country of origin: This concerns both environmental protection and human rights. Species protection measures, anti-corruption measures, labor rights, the UN Declaration on the Rights of Indigenous Peoples, trade law, etc. have been complied with.
  • Due diligence declaration available: A risk assessment has been carried out for the product, the due diligence obligations have been complied with and there is no or only a negligible risk of deforestation.

What requirements apply to the different EUDR market roles?

The EU Deforestation Regulation categorizes affected companies as Traders and Operators, and as SMEs and non-SMEs (note: the EUDR uses its own criteria for this).

This leads to different requirements – for example:

  • First placers on the market (importers) are required under the EUDR to conduct a risk assessment, mitigate risks, and submit a due diligence statement via the EU’s “Traces” system. In addition, non-SMEs are subject to reporting obligations.
  • First downstream operators must store and retain this due diligence statement (DDS) and only validate it in the case of substantiated concerns. They are not required to pass the DDS on to further downstream operators and traders (their customers).
  • Small and micro primary operators in low-risk countries (e.g., small forest owners in the EU): this is also a new category with simplified rules. A one-time, simplified declaration is possible — without geolocation data, requiring only the postal address. The aim is to relieve the burden on small farmers within the EU.

As a first step, use our free check to easily find out which category your company falls into and which obligations apply to you.

How can importers prepare? Practical steps for EUDR implementation

Step 1: Collect EUDR data

Gather detailed information about your products and raw materials — including descriptions, volumes, suppliers, and countries of origin.

The EUDR requires geo-location data for every plot where relevant commodities are produced, including production dates — retroactively from December 31, 2020.

Ensure proof that all legal rights are respected in the country of origin.

Step 2: Conduct risk assessment

Evaluate the deforestation risk for any new product or commodity.

Factors include:

  • Country of origin
  • Deforestation trends
  • Political and social conditions
  • Supply chain complexity

The EU will provide a benchmarking system categorizing countries by risk level. Only products with no or negligible risk may enter the EU market.

Step 3: Mitigate risks

If risks are identified, work with suppliers to reduce them. Develop new codes of conduct, strategies, and control measures. Verify compliance via supplier audits or documentation

Step 4: Document and report

Companies must maintain detailed records and submit reports.

For every batch, a due diligence statement or EUDR compliance confirmation must be included — customs will verify compliance based on risk assessments.

Except for SMEs, companies must also publicly report on risk assessments, due diligence processes, and mitigation measures. If your company is subject to the CSRD, you can integrate EUDR reporting into your sustainability report.

What are the EUDR sanctions?

Violations or non-compliance may result in:

  • Confiscation of unlawful profits
  • Fines proportional to the damage caused, minimum 4% of annual turnover
  • Seizure of goods or products
  • Temporary import bans
  • Exclusion from public funding or tenders
  • Public naming and shaming of the company and its violation

Background on the EUDR

In the past 30 years, global deforestation has wiped out an area larger than the EU. Forest loss accelerates climate change and biodiversity loss.

The EUDR follows the EU Timber Regulation (EUTR) from 2013, which was criticized for weak enforcement. As part of the European Green Deal, the EUDR strengthens these efforts.

From 2025 onwards, it will be prohibited to place, make available, or export certain products in the EU market if they are linked to deforestation or forest degradation since January 2021 — regardless of whether the forest is in Germany, Romania, or Brazil.

EUDR Compliance Guide: From Data Collection to Due Diligence Statement

Don’t get lost in the EUDR. Download our free guide with handy checklists, infographics, and FAQs!

*This information is summarized editorial content and should not be considered legal advice. VERSO assumes no liability. 

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Best practices in the areas of ESG and sustainable supply chains
  • Developed with expertise from 12+ years of sustainability management
  • Sustainability events and much more.

Get to know the software!

ESG in der Lieferkette
14.02.2025

ESG in the Supply Chain: 19+1 To-Dos

Requirements as far as the eye can see: Where should you best start to establish ESG compliance along the supply chain and unlock the many ESG opportunities for your company? This article shows you how – with 19 to-dos and one bonus tip.

For procurement and supply chain managers, regulations such as the LkSG, CSDDD, CSRD, EUDR, CBAM, and PPWR mean more documentation requirements, higher transparency demands, and increasing pressure on suppliers.

Despite all these challenges, ESG compliance in the supply chain is an opportunity to identify risks early, reduce costs, and strengthen your own market position. With the right strategy, sustainability can shift from a cost center to a profit center.

But where should you start? This practical checklist with 19 actionable to-dos and one bonus tip provides clarity.

Feel free to share this article if you found it helpful.

Review and prioritize ESG regulations

1. Assess which ESG regulations may affect your supply chain

Selection of supply chain regulations applicable in 2025 Supply chain regulations applicable after 2025
LkSG Forced Labour Regulation
CSRD CSDDD
EU-Taxonomy ESPR / Digital Product Passport
CBAM Right to Repair
EU-ETS EUDR
Additional regulations such as the EU Battery Regulation or the Circular Economy Act PPWR

2. Review which regulations apply to your company and when – some regulations (e.g., CSRD, CSDDD, PPWR and EUDR) are implemented in phases

3. For most companies, CSRD, LkSG/CSDDD, CBAM, PPWR and EUDR are currently the most relevant

Read more:

Collect ESG data in the supply chain and increase transparency

4. Obtain up-to-date supplier master data and define points of contact

5. Use standardized ESG questionnaires for suppliers and verify them through targeted audits

6. Capture Scope 3 emissions and identify hotspots

7. Define climate targets for the supply chain and implement a climate strategy

Read more:

Identify and manage ESG risks

8. Review suppliers for human rights, environmental, and climate-related risks (abstract, concrete, and event-driven risk analysis)

9. Establish measures for risk prevention and implement remedial actions

10. Establish a holistic, future-proof management system for supply chain risks

Strengthen supplier management for long-term ESG compliance

11. Embed ESG criteria in supplier contracts and communicate a Code of Conduct

12. Assess the ESG maturity level of suppliers

13. Provide training and support for suppliers to improve ESG standards

14. Regularly review supplier ESG performance

Review IT systems and optimize data management

15. Review the interoperability of your IT systems

16. Implement digital ESG data management to ensure full transparency and communication with suppliers

Check off ESG reporting and ensure compliance

17. Consolidate data and standardize reporting processes

18. Ensure regular reporting and leverage synergies: Some BAFA requirements (LkSG) overlap with the ESRS (CSRD), EUDR, and CBAM data and can be reused for CSRD reporting

19. Involve external auditors (e.g., certified public accountants) at an early stage

Bonus tip: How to achieve ESG compliance in the supply chain with less effort

Admittedly, ESG requirements for supply chain managers are demanding. However, with the right strategy, they can be addressed efficiently. Use this checklist as a starting point to make your supply chain ESG-compliant. A more detailed breakdown is available in our practical guide to sustainable supply chains.

Our bonus tip: The VERSO Supply Chain Hub creates transparency and supports you efficiently in implementing the LkSG, CSRD, CBAM, PPWR and EUDR – automated and legally compliant.

Practical guide to sustainable supply chains

This guide provides an overview of all key obligations and requirements across 17 pages.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter

Sign up and receive regular news about:

  • Current ESG topics and legislative changes
  • Individual advice from the VERSO experts
  • News about VERSO
  • Sustainability Events and more
Sign up now!

Supplier Management in der Lieferkette: Zwei Personen in einer Fabrikhalle als Symbol für nachhaltige Lieferantenbeziehungen und ESG-Compliance
20.12.2024

Sustainability in the Supply Chain: Best Practices in Supplier Management

Supplier management is key to ESG compliance. Learn how to strengthen supplier relationships in a targeted way. This not only creates greater supply chain transparency but also lays the foundation for resilient, long-term partnerships. Particularly in the context of CSRD, the German Supply Chain Act (LkSG), and EUDR, structured supplier management is becoming an increasingly critical success factor.

Your supply chain is only as strong as its weakest link. But how can you ensure that you can rely on your suppliers throughout the sustainable transformation of your supply chain? Supplier management is key. This article explains how to create transparency, minimize risks, and strategically strengthen supplier relationships with the VERSO Supply Chain Hub.

Why supplier management should be part of your sustainability strategy

Sustainable supply chains require teamwork. Companies that want to make progress need to work closely with their suppliers. Two reasons are particularly important.

Supply chain transparency requires collaboration

The CSRD requires companies to ensure comprehensive transparency across the entire value chain. Without active supplier collaboration, it is nearly impossible to establish the necessary processes and obtain relevant information on working conditions, carbon emissions, or product compliance.

A chain is only as strong as its weakest link

The second aspect: If your entire supply chain is to become sustainable, every part of that supply chain must also be sustainable. This may sound entirely logical at first. In practice, it means that you should not simply impose sustainability requirements from the top down and hope that your expectations are met. Instead, treat sustainability as a joint project that you develop together with your suppliers. This also means, for example, that some suppliers will require substantial support throughout the sustainable transformation. True resilience can only be achieved if supplier management strengthens every link in your chain.

Challenges in supplier management

Establishing effective supplier management is easier said than done. Companies often face challenges such as poor data quality, complex requirements, and inadequate processes. However, with the right approaches, you can successfully address these supplier management challenges.

Incomplete data an a lack of transparency

A common challenge in supplier management is the lack of reliable data. Precise information on working conditions, carbon emissions, or product compliance is often unavailable. However, requesting data once a year is not enough. A better approach is to continuously monitor your suppliers and their ESG compliance.

Complexity goes beyond sustainability

Supplier management involves more than simply imposing sustainability targets. Companies must manage certificates, monitor and assess risks, account for sanctions, and much more. Sustainability should not be viewed in isolation but integrated into a comprehensive supplier assessment.

Poor supplier selection and insufficient development

Supplier selection and development are another critical area. Clear processes for assessment and further development are often lacking. In addition, suppliers are frequently reviewed only during audits. Supporting suppliers on their journey toward greater sustainability takes time and targeted measures. Data should not only be collected but also actively used between audits to drive progress. At the same time, communication and documentation remain key factors, particularly during supplier nomination.

Clear communication and partnership

Transparency and open communication are essential. Focus on a collaborative approach. Base your discussions on data to promote transparency and trust. On-site visits and targeted audits create a foundation for long-term collaboration and tailored improvements.

Sustainable supply chains cannot be created at the push of a button

“Sustainable procurement cannot be implemented as a side task. The journey requires new structures and continuously ties up resources,” emphasizes our supply chain expert Klaus Wiesen in an interview on sustainable supply chains. The problem is that many companies delay sustainability for as long as possible and then come under enormous pressure shortly before the deadline.

Practical guide to sustainable supply chains

Gain an overview of all key obligations and requirements. You will also receive practical tips for building sustainable, future-ready supply chains.

Our tips for a strong supplier management

How can you overcome these challenges and lay the foundation for strong supplier relationships? Here are our top tips for effective supplier management—and how the VERSO Supply Chain Hub can support you.

Choose reliable suppliers from the start

  • Establish clear standards for supplier nomination, such as sustainability criteria and financial stability.
  • Continuously monitor your criteria in the VERSO Supply Chain Hub.

Communicate Clearly and Strengthen Partnerships Through Active Supplier Management

  • Base discussions on data and ensure transparent communication.
  • Promote collaborative relationships through regular audits and on-site visits.

Establish binding standards and procurement policies

  • If you have not already done so, develop binding procurement policies that include sustainability targets, compliance requirements, and quality standards. Do not simply have suppliers sign them—actively verify compliance.
  • Monitor compliance and deviations with the VERSO Supply Chain Hub.

Actively support supplier development

  • Support suppliers through training and joint projects.
  • Make your sustainability strategy a recurring agenda item in supplier discussions.
  • Use monitoring tools to document progress and secure supplier commitment.

Collect data continuously

  • Do not collect the required data only at isolated points in time. Monitor it continuously.
  • Make data submission as easy as possible for your suppliers—for example, through standardized requests in the VERSO Supply Chain Hub.

Use targeted tools in supplier management

  • Do not make processes unnecessarily complicated. A digital platform can significantly simplify data management, monitoring, and risk oversight.
  • The VERSO Supply Chain Hub offers numerous features specifically designed for Supplier Relationship Management (SRM).

Practical guide Supplier Risk Management

Our practical guide shows you how to manage supplier risks in a pragmatic and structured way in mid-sized companies.

Supplier management as the key to ESG compliance

Strong supplier management lays the foundation for sustainable and resilient supply chains. Clear processes, transparent communication, and the targeted use of the VERSO Supply Chain Hub enable companies to meet regulatory requirements such as the CSRD while securing long-term competitive advantages.

Move straight from theory to practice and discover in a free, no-obligation demo how VERSO can make your supplier management future-ready.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Current ESG topics and legislative changes
  • Individual advice from the VERSO experts
  • News about VERSO
  • Sustainability Events and more
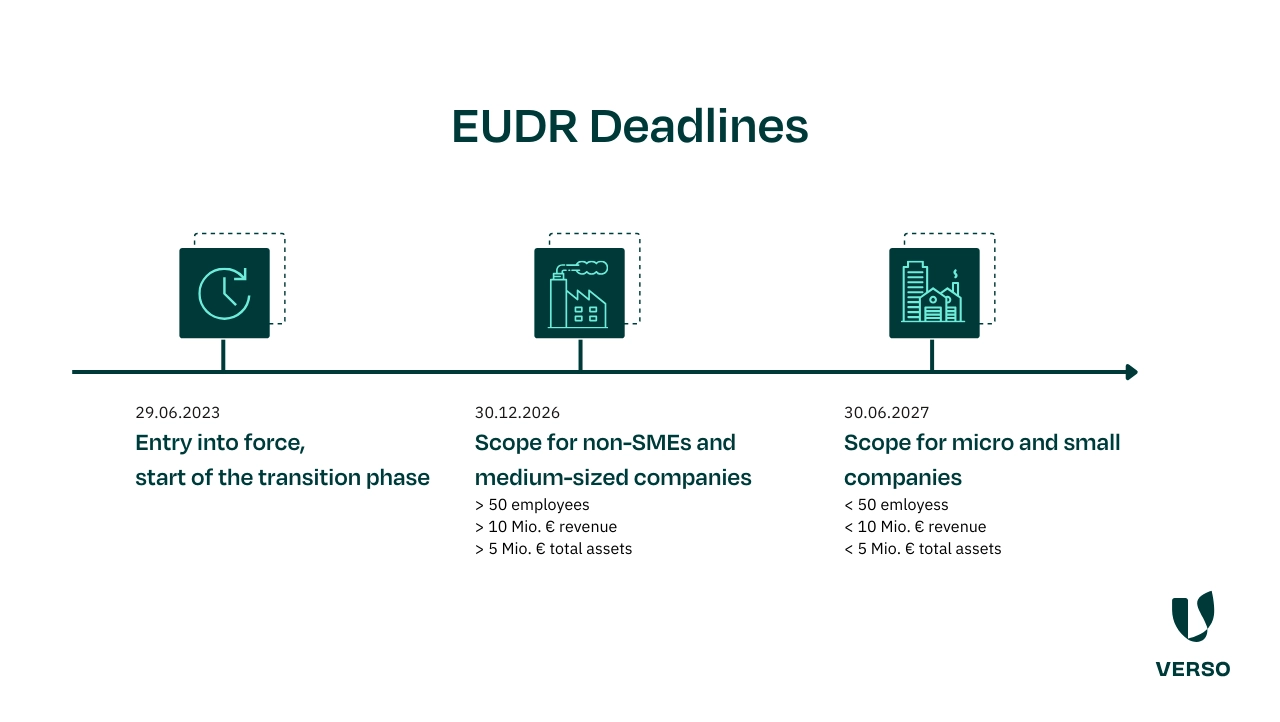
Sign up now!

Blog Fahrradbranche Lieferkette
09.09.2024

Compliance in the Supply Chain: How the Bicycle Industry Is Mastering the Task

Sustainability regulatory obligations are increasing and compliance in the supply chain is becoming ever more important. Read our article to find out how companies fullfil the ESG requirements for the supply chain and how VERSO specifically supports the bicycle industry in this task.

The economy is undergoing a profound change. More and more companies are integrating sustainability into their business models. This topic is also becoming increasingly important in the bicycle industry – especially in relation to the supply chain, as this is where the greatest risks and the greatest impact of bicycle manufacturers lie.

Two factors play a key role. Firstly, many companies are launching sustainable initiatives to improve their environmental footprint. This enables them to generate business value and Competitive advantages.

On the other hand, regulatory pressure is growing – including throughtheCSRD reporting obligation, the CO2-border-adjustment mechanism CBAM and the EUDR regulation for deforestation-free supply chains. Compliance with sustainability requirements is becoming mandatory.

CSRD, EUDR and CBAM: New requirements for compliance in the supply chain

There are numerous new requirements in the area of sustainability that also affect the bicycle industry. The CSRD, the EU directive on sustainability reporting, plays a major role. Companies have to provide extensive ESG information – and not only consider their own company, but also the supply chain. We have summarised what exactly is required in our blog post „CSRD and the supply chain”. However, the industry is also confronted with new obligations arising from the use of certain raw materials. For example, companies are subject to the EUDR because rubber is used for bicycle tyres. By using CO2-intensive materials such as aluminium or steel, companies may also be affected by CBAM. Both regulations include an assessment of certain raw materials as well as a documentation and reporting obligation. Those who create transparency here and thus address the risks identified have created the basis for fulfilling almost all requirements and compliance in the supply chain.

Compliance in the supply chain: the challenge of a complex supply chain

Cycling is – apart from walking – the most environmentally friendly form of transport: emission-free, quiet, efficient and climate-friendly. However, this only applies to pedalling. When it comes to the production of bicycles, especially e-bikes, the balance is somewhat different.

In addition to emissions – including CO2-intensive materials – the use of high-risk materials also plays a role. “Raw materials for motors, electronics and batteries are associated with major sustainability risks,” explains Klaus Wiesen, Head of Sustainable Supply Chain at VERSO. In addition, the bicycle industry often has complex supply chains. This makes it all the more important to create transparency with regard to these issues and reduce risks.

The complexity of the supply chain results from the large number of players involved in the production of the numerous components of a bicycle or e-bike. These players are distributed internationally, which results in different framework conditions and long transport routes.

Compared to conventional bicycles, e-bikes bring additional challenges. New technologies and raw materials for the drive and battery have become relevant in production. Here, bicycle manufacturers are competing with industries such as the IT sector, with which they previously had little contact.

CSRD and supply chain: these disclosures are required

The CSRD obliges companies to provide extensive information on the supply chain. Find out what information is required and what opportunities and risks arise from the EU directive.

The growing importance of transparency and data management

“Transparency in the supply chain is the key to complying with current and future regulations,” emphasises Klaus Wiesen. Many VERSO customers have voluntarily established corresponding processes before they are obliged to do so by regulations such as the Supply Chain Act (LkSG).

Riese Müller is a pioneer in the bicycle industry and aims to be the most sustainable company in the e-bike sector by 2025. With the VERSO Supply Chain Hub the company creates the necessary transparency in the supply chain and promotes its suppliers in terms of sustainability. Riese Müller is also improving risk management and supply chain mapping to ensure compliance in the supply chain.

However, not all companies in the bicycle industry are that advanced. A key problem is the collection and management of data along the supply chain. Smaller manufacturers in particular have some catching up to do.

“Many companies have hardly collected any structured data, which now presents them with considerable challenges if they want to fulfil the requirements of CSRD, CBAM, EUDR and other regulations,” says Klaus Wiesen. This is where VERSO comes in and offers solutions to support companies in realigning their processes and fulfilling the requirements.

Compliance in the supply chain: benefiting from the network

VERSO is the bicycle industry’s leading platform for sustainability in the supply chain. Their customers include German companies such as Riese Müller as well as international manufacturers – for example from the Netherlands, Switzerland and the USA.

“As there is a large overlap in the supplier base in the bicycle industry, our customers benefit from the networks created and stored in our software,” explains Klaus Wiesen. All customers also benefit from learning effects from previous projects. VERSO integrates new regulations into its software at an early stage to ensure future compliance in the supply chain.

EUDR: Everything you need to know

The EU regulation for deforestation-free supply chains (EUDR) aims to prevent the ongoing deforestation of forests. In our article, we answer the most important questions about the EUDR.

Leveraging supply chain ompliance as a chance for the bicycle industry

The regulations are not only associated with additional tasks. They also open up new opportunities for companies.

One example is risk management. Companies in the bicycle industry have suffered particularly badly from supply bottlenecks in the past. Resilience in the supply chain has therefore become an important issue. By identifying risks (e.g. political instability, natural disasters or human rights violations), a company can take measures to minimize or avoid the impact of these risks. This ensures robust supply chains.

Bicycle manufacturers’ customers often attach great importance to sustainability. Those who fulfill the compliance requirements show that their company takes responsibility for ethical and environmentally friendly standards in the supply chain. This creates trust, provides a competitive advantage and contributes to the long-term success and good reputation of the brand.

Avoiding reputational damage and penalties also plays a role. Companies that do not fulfill their regulatory obligations must expect sanctions. We have summarised possible penalties in the blog post „Sanctions at a glance: The cost of mistakes in reporting and implementing sustainability” for an easy overview.

Holistic sustainability management at VERSO

In order to fulfill the requirements, companies should prepare for the new regulations at an early stage. Thanks to our expertise in the bicycle industry (among others) VERSO is the ideal partner. “With the VERSO Supply Chain Hub we have been supporting our customers for years with transparency in the supply chain and the fulfillment of their due diligence obligations. Our software solution enables optimized preparation for current and future regulations,’ emphasizes Klaus Wiesen.

The supply chain harbors the greatest risks and has the greatest impact in the bicycle industry. However, a holistic view of a company is necessary, particularly with regard to CSRD. This includes the upstream and downstream value chain as well as the company’s own business activities. VERSO offers an all-in-one solution here.

With the VERSO ESG Hub you can collect all relevant data and create a meaningful sustainability report. With the Climate Hub the corporate carbon footprint is calculated and a climate strategy is mapped. The VERSO sustainability experts will support you throughout the entire process. Furthermore, you can gain additional know-how about sustainability in our VERSO Academy courses.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers
CSRD und Lieferkette - Was der Einkauf beachten muss
17.06.2024

CSRD and Supply Chain: What Procurement Needs to Consider

The CSRD with its ESRS standards is not only a lot of work, it also has a major impact on companies: This is because you have to make extensive ESG disclosures – and not only look at your own company, but also at the supply chain. Read here what purchasing departments need to consider and what opportunities and risks arise from the EU directive.

The CSRD (Corporate Sustainability Reporting Directive) has applied to the first companies since January 2024, and others are gradually being added. Ultimately, around 50,000 companies in Europe will be obliged to publish a report with comprehensive information on ESG (environmental, social and governance) issues.

The ESRS, the European Sustainability Reporting Standards, were also introduced with the CSRD. For the first time in the EU, they provide a standardized framework for the preparation of a sustainability report – in simple terms: which ESG information is required and in what form it must be reported.

It is important to note that the reporting obligation not only relates to the company itself, but also extends to the entire value chain. In this blog post, we look at the upstream value chain – i.e. the supply chain. And this is where companies subject to CSRD reporting requirements can quickly run into problems: they need a lot of information from their suppliers and the data situation is often inadequate – according to the Bertelsmann Stiftung’s Sustainability Transformation Monitor 2024. With VERSO, you can master this challenge. Our Supply Chain Hub creates transparency in the supply chain and enables you to analyze risks, develop targeted measures and comply with reporting obligations. We will now take a closer look at these disclosure requirements within the framework of the CSRD and the impact on purchasing.

CSRD and supply chain: What needs to be reported?

The CSRD demands a lot from companies: the ESRS comprises around 1150 data points and over 100 of these relate to the supply chain. Purchasing is therefore an important player in the reporting process.

The information involved can be roughly summarized as follows: The ESG report must contain information on environmental and social IROs (impacts, risks and opportunities) in the supply chain as well as measures related to the IROs. If your company is affected by the LkSG, you will probably recognize some disclosure requirements and can realize synergies: This is because some BAFA requirements overlap with the ESRS.

Bei den ESRS gibt es sektorunabhängige Standards und sektorspezifische Standards. Die Sektorunabhängigen Standards teilen sich in die Bereiche Allgemeines, Umwelt, Soziales und Unternehmensführung. Die Allgemeinen Standards sind verpflcihtend für alle Unternehmen, die Themenstandards sind je nach doppelter Wesentlichkeit berichtspflichtig oder nicht.

But what does this mean in detail? To answer this question, let’s take a closer look at some ESRS standards and clarify how they relate to the supply chain.

ESRS E1 – the climate protection standard

The name says it all: ESRS E1 is about climate protection – in your company and in your supply chain. Your company must therefore not only disclose its own greenhouse gas emissions, but also the CO2 emissions in the upstream and downstream value chain – i.e. in Scope 3. Incidentally, the majority of companies generate the most emissions in this category.
E1 also requires companies to set themselves climate targets. Transparency about the targets and measures of their own suppliers is crucial in this respect.

ESRS E5 – Resource utilization and circular economy

The supply chain naturally plays an important role in ESRS E5, as many resources are obtained or processed here. For example, the CSRD asks for:

  • Measures to avoid the generation of waste
  • Resource utilization
  • Measures to promote the circular economy
  • Cooperation or initiatives to improve the recyclability of products and materials


ESRS S2 – Workforce in the value chain

The fact that the ESRS S2 also relates to the supply chain and entails disclosure obligations is already in the name, so to speak. Among other things, the CSRD is concerned here with how your company fulfills the due diligence obligations. This means How do you Ensure compliance with human rights, labor standards andgood working conditions at suppliers? The CSRD does not require much more than the LkSG. You should also show whether there is a complaints management or whistleblower system for workers in the supply chain, how you handle complaints and resolve any problems raised.

ESRS S3 – Affected communities

The ESRS S3 addresses the impacts that your company’s operations, products or services, and upstream and downstream value chains have on “affected communities”. This refers to people and groups who live or work in the same area as a company. The standard also explicitly refers to impacts on indigenous peoples. Impacts can arise, for example, from truck transportation, the extraction of raw materials or controversial land use.

ESRS G1 – Company policy

With regard to the supply chain, your company must disclose the following:

  • Management of relationships with suppliers, payment practices, in particular with regard to late payments to small and medium-sized enterprises
  • Strategies for detecting and preventing corruption and bribery, including training for suppliers

However, you do not have to provide information on every standard in your CSRD report. This depends on whether a topic is material for your company. VERSO offers you an AI-supported materiality analysis here. In our white paper “All information on the ESRS” you will also find further detailed information on the European standards, in particular on the transition periods.

Is your purchasing department ready for the ESG requirements?

Companies are now affected by a large number of sustainability requirements – and purchasing is no exception.
Use our checklist to find out whether your purchasing organization is optimally prepared for ESG requirements.

CSRD and the supply chain: opportunities and risks for procurement

The CSRD is a major challenge – we can’t hide that and we don’t want to. With almost 1200 data points, ESRS reporting is a mammoth task. It is complex and resource-intensive. But with the right support, you can manage it – we will be happy to assist you with the sustainable transformation. What’s more, the CSRD doesn’t just end with a sustainability report.

The fact that your company is systematically addressing the issue of sustainability opens up great opportunities. The double materiality analysis and reporting will make opportunities and risks in the supply chain more visible. This enables your company to address these in a targeted manner. Sustainability requirements can trigger innovations, such as the use of environmentally friendly materials or the optimization of logistics processes.

Many customers also tell us that the reporting process has enabled them to get to know their suppliers even better. The increased transparency ensures better and more sustainable supply chain practices. By working closely together, you strengthen long-term partnerships and thus improve the stability and efficiency of the supply chain. The reporting process promotes digital development. Software specialized in CSRD, LkSG and CBAM requirements helps monitor the supply chain and ensures compliance with legal requirements. It can collect and process the necessary large volumes of data.

Risk management for sustainability in the supply chain

In our white paper, you will learn how to implement the requirements of the German Supply Chain Act (LkSG) in a future-proof manner through digitalization and collaboration.

How does CSRD influence purchasing and the supply chain?

CSRD has a major impact on purchasing and requires a high degree of transparency and responsibility. Your company must collect and provide detailed information and comply with legal due diligence obligations in relation to environmental and social standards. This includes a new assessment in the purchasing process to ensure that suppliers comply with sustainability requirements.

So you need to be even more careful about who your company does business with.
Teamwork is also required when it comes to climate change. Climate change and extreme weather will affect us all. That’s why we need to act together to slow down climate change and reduce its impact.

Climate protection measures must not stop at the gates of your own company: Together with your suppliers, you can implement initiatives that help reduce greenhouse gas emissions.
You can find specific tips for decarbonizing your supply chain in the blog post “Why is climate protection in the supply chain relevant?”.

How VERSO supports you in implementing the CSRD

VERSO offers you the all-in-one package for implementing the CSRD. The EU directive makes the topic of sustainability in the supply chain even more relevant, as companies must now also report robustly on sustainability activities in the supply chain. The VERSO Supply Chain Hub helps procurement to record the necessary data in the supply chain, monitor suppliers and provide the required reporting key figures with minimal effort.

We round off the package for implementing your CSRD obligations with additional software solutions and consulting services. With VERSO, you can carry out an AI-supported materiality analysis. In the ESG Hub, you collect all relevant data and create a meaningful sustainability report. The Climate Hub supports you with your carbon footprint and decarbonization strategy. And in the VERSO Academy, you will acquire the necessary knowledge about CSRD and ESRS.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers

Get to know the software!

Secret Link