Ältere Frau arbeitet am Laptop und guckt sehr konzentriert
19.08.2026

ESG sanctions at a glance: the cost of mistakes in reporting and supply chain obligations

A slap on the wrist and, if it becomes public, a brief outcry from the public: until a few years ago, companies didn’t have to worry too much if they put sustainability on the back burner or engaged in greenwashing. The Omnibus package does little to change that: the EU has pushed back deadlines and reduced the number of companies affected, but it has not abolished the sanctions.

Companies that breach ESG and supply chain obligations risk fines in the millions, penalties calculated as a percentage of annual turnover, seized goods or exclusion from public contracts, depending on the regulation. The EU Omnibus package made some rules less strict in 2026 and narrowed the group of companies they apply to. This article shows which sanctions apply under the CSRD, CSDDD, LkSG, CBAM, EUDR, PPWR, DPP and EmpCo, and from when.

As of September 2026. This article reflects the EU Omnibus I package, the planned reform of the LkSG and the latest postponement of the EUDR. This information is editorial content that should not be construed as legal advice. VERSO accepts no liability.

ESG sanctions at a glance: possible sanctions, companies affected and start date by regulation (as of September 2026)
Regulation Possible sanctions Who is affected? From when?
CSRD Planned under the HGB: fines of up to €10 million or 5% of annual turnover (capital market-oriented companies), prison sentences of up to 3 years More than 1,000 employees and over €450 million net turnover Once the German implementation act enters into force (legislative process ongoing)
CSDDD Up to 3% of global net turnover, civil liability under national law More than 5,000 employees and over €1.5 billion net turnover Applies from 26 July 2029
LkSG Previously up to €8 million or 2% of global annual turnover, exclusion from public procurement; in future only for serious violations 1,000 or more employees in Germany In force since 2023, reform in the legislative process
EU ETS €100 per tonne of CO₂e without an allowance (adjusted for inflation) Operators of installations covered by emissions trading In force
CBAM Same as EU ETS per missing certificate, revocation of declarant status Importers of 50 tonnes or more of CBAM goods per year Definitive phase since 1 January 2026
EUDR At least 4% of annual EU turnover, confiscation of goods, import bans, exclusion from public procurement Operators and traders handling relevant commodities 30 Dec 2026 (large/medium), 30 June 2027 (micro/small)
PPWR Fines of up to €200,000 under the German VerpackDG, distribution bans, public register entries Manufacturers, importers and distributors of packaging Since 12 August 2026
EmpCo Warning letters, cease-and-desist claims; fines of up to €50,000 or 4% of the affected annual EU turnover All companies making environmental claims to consumers Since 27 September 2026
DPP (ESPR) Fines (level set nationally), withdrawal and recall, import bans, exclusion from public procurement Manufacturers and companies placing the relevant product group on the market Battery passport from 18 Feb 2027, other product groups to follow

Stress-free CSRD compliance

Make CSRD as easy as possible: Our new CSRD Suite provides tools and support for every stage of CSRD compliance.

What sanctions apply for breaches of the CSRD, EU Taxonomy and SFDR?

There is no EU-wide, uniform set of sanctions for the CSRD. Each member state decides how to penalise errors in sustainability reporting. In Germany, this will be governed by the CSRD Implementation Act, which is still going through the legislative process. Until it enters into force, companies that were already required to report remain subject to the HGB rules on the non-financial statement. The government draft is based on the existing criminal and administrative penalty provisions in §331 and §334 HGB. In figures, this means:

  • Prison sentences of up to 3 years
  • For members of authorized representative bodies or supervisory boards of a corporation: prison sentences of up to 3 years; companies face fines of up to 2 million euros or twice the economic benefit they have derived from the incorrect report – whichever is higher.
  • For capital market-oriented companies: Fines of up to 10 million euros, 5 percent of annual turnover or twice the economic benefit – the highest amount is also chosen here.

On top of this – as the fermented icing on the cake, so to speak – there may also be legal action for breach of competition law, exclusion from public procurement procedures and “naming and shaming”, i.e. publicity including loss of reputation.

Important to know: Only intentional errors and errors due to gross negligence are punishable.

In the next few years, the first court proceedings will show the exact direction of sanctions for breaches of the EU taxonomy, CSRD and SFDR.

Read more:

Practical guide to CSRD

Our practical guide, including a checklist, will help you prepare for CSRD reporting.
Find out what challenges there are and how you can overcome them.

Sanctions for LkSG and CSDDD

How high are the fines under the CSDDD?

With the Omnibus I package, the EU significantly weakened the CSDDD, the European supply chain directive, in 2026. This also affects the sanctions. Companies that breach their due diligence obligations for people and the environment face:

  • Fines of up to 3% of global net turnover.
  • Civil liability for damages. The EU-wide harmonised liability rule was removed; liability is now governed by the law of each member state.
  • Naming and shaming and exclusion from public procurement.

What does a breach of the German Supply Chain Act (LkSG) cost?

In contrast to the CSDDD, the German Supply Chain Act does not create its own civil liability. The LkSG requires companies to meet human rights and environmental due diligence obligations in their own business operations and towards direct suppliers. For indirect suppliers, the obligations apply as soon as the company has substantiated knowledge of possible violations. Risks must be identified, documented and eliminated or at least minimised.

Previous fine framework: fines of up to 8 million euros. For companies with an annual turnover of more than 400 million euros, the fine increases to up to 2% of global annual turnover. And: companies can be excluded from public procurement.

What is set to change: in September 2025, the German government adopted a reform of the LkSG; the legislative process is still ongoing. Under the reform, the annual reporting obligation is to be abolished retroactively. Fines are only to be imposed for serious violations that lead to grave human rights abuses. The due diligence obligations themselves remain in place. In practice, the Federal Office for Economic Affairs and Export Control (BAFA) has already suspended the reporting obligation. In the medium term, the national implementation of the CSDDD is to replace the LkSG.

Read more:

EU ETS and CBAM sanctions

EU ETS

With the EU Emissions Trading System (EU ETS), the EU aims to cap the emissions of the member states. Companies only have a certain amount of freedom to emit emissions – otherwise certificates must be purchased. Non-compliance could result in fines:

  • 100 euros per metric ton of CO2 equivalents emitted without a certificate (adjusted annually for inflation)

In order to avoid certificate prices on the one hand and sanctions on the other, some companies relocated their production to non-EU countries (“carbon leakage”). The CBAM was therefore also introduced as part of the EU ETS reform.

What sanctions apply under the CBAM?

The definitive phase of the CBAM has been running since 1 January 2026. Companies that import certain emission-intensive goods such as steel, aluminium, cement or fertilisers from non-EU countries need the status of authorised CBAM declarant and must buy and surrender CBAM certificates for the embedded emissions.

Relief from the Omnibus package: companies that import less than 50 tonnes of CBAM goods per year are exempt from the obligations. This does not apply to electricity and hydrogen.

The so-called “climate tariff” supplements the EU ETS and provides for the following sanctions:

  • Missing certificates: in accordance with the EU ETS, fines of EUR 100 per tonne of CO2 equivalent are imposed.
  • Anyone importing CBAM goods without the status of authorized declarant must expect even higher penalties.
  • In the event of violations, the authorised declarant status can be revoked. The company may then no longer import CBAM goods.
  • For the transitional phase (2023 to 2025), incomplete, incorrect or missing CBAM reports were subject to penalties of 10 to 50 euros per tonne of unreported emissions.


Read more:

Is your purchasing department ready for the ESG requirements?

Companies are now affected by a large number of sustainability requirements – and purchasing is no exception. Use our checklist to find out whether your purchasing organization is optimally prepared for ESG requirements.

When do EUDR sanctions apply?

Supply chain officers and buyers must prepare themselves for even more sanctions. If you place products on the EU internal market whose production has come at the expense of forests, you could face the following penalties under the EUDR:

  • Skimming off profits unlawfully made as a result of non-compliance with the EUDR
  • Fines in proportion to forest damage and value of goods, but at least 4 % of annual turnover
  • Seizure of goods or products
  • Temporary import bans
  • Exclusion from public funds and public tenders
  • Inclusion in a public list incl.
    Information on the violation

Also important: The EU has postponed the application of the EUDR once again. The obligations apply from 30 December 2026 for large and medium-sized companies and all traders, and from 30 June 2027 for micro and small enterprises. From then on, you may only place the relevant goods on the EU market if geolocation data and proof of origin are available. Keep this in mind today when ordering goods that will reach the EU single market from the end of December.

Read more:

What fines apply under the PPWR?

The EU Packaging and Packaging Waste Regulation (PPWR) has applied since 12 August 2026. In Germany, the Packaging Law Implementation Act (VerpackDG) governs how violations are penalised. It replaces the previous Packaging Act (VerpackG). Depending on the severity of the violation, companies face:

  • Fines of up to 200,000 euros, for example for placing packaging on the market without the required participation in a take-back system or for selling despite a distribution ban
  • Fines of up to 100,000 euros for breaches of registration, reporting and documentation obligations or of take-back and deposit obligations
  • Fines of up to 10,000 euros for certain formal violations
  • Distribution bans and public entries in the register

The PPWR introduces new sanctionable offences, such as missing declarations of conformity, missing technical documentation and breaches of the requirements on recyclability and recycled content. The European Commission recommends that authorities initially focus on warnings and corrective measures.

Read more:

What penalties apply for greenwashing under the EmpCo?

Since 27 September 2026, EmpCo has regulated misleading environmental claims and unlawful sustainability labels more strictly. In Germany, the requirements are implemented through the Act Against Unfair Competition. Violations may therefore primarily result in warnings, cease-and-desist claims, interim injunctions and legal action by competitors or associations.

In certain cases, fines may also apply. For widespread infringements, the fine can amount to up to EUR 50,000. For companies with annual revenue of more than EUR 1.25 million, the fine may amount to up to 4% of the affected EU annual revenue.

The European Commission halted the Green Claims Directive, which was intended to regulate environmental claims in addition, in June 2025. This makes EmpCo the relevant framework for environmental claims.

Read more:

What sanctions apply to the Digital Product Passport (DPP)?

With the Ecodesign for Sustainable Products Regulation (ESPR), the EU is gradually introducing the Digital Product Passport. It brings together information on a product’s materials, origin, reparability and environmental impact. Companies that fail to meet the requirements face sanctions. Member states set the level of fines, but the ESPR already provides for the following measures:

  • Fines
  • Withdrawal and recall of products
  • Import bans
  • Temporary exclusion from public procurement

The battery passport will be the first mandatory product passport from 18 February 2027. In Germany, incorrect or incomplete information can lead to fines of up to 10,000 euros. For other product groups such as textiles and furniture, the EU has yet to define the requirements.

Frequently asked questions about ESG sanctions

Which ESG regulations provide for sanctions?

Sanctions apply under the CSRD, the CSDDD, the German Supply Chain Due Diligence Act (LkSG), the Carbon Border Adjustment Mechanism (CBAM), the EU Deforestation Regulation (EUDR) and the EmpCo directive against greenwashing, among others. The type and amount of sanctions differ by regulation.

What is the highest possible fine?

The highest fines are set by the turnover-based regulations. Under the CSDDD, fines of up to 3% of global net turnover are possible; under the EUDR, the maximum is at least 4% of annual EU turnover. On top of that come consequences such as exclusion from public contracts or confiscation of goods.

Has the EU Omnibus package changed the sanctions?

Yes. The Omnibus I package weakened the CSDDD: it now only applies to companies with 5,000 or more employees and 1.5 billion euros in turnover, from 26 July 2029, with a maximum fine of 3% instead of 5% and without EU-wide harmonised civil liability. For the CSRD, the group of companies required to report was reduced, and the CBAM now has an exemption for imports below 50 tonnes per year.

Does the German Supply Chain Act still apply?

Yes. The due diligence obligations under the LkSG continue to apply. A reform is set to abolish the reporting obligation and limit fines to serious violations; in practice, BAFA has already suspended the reporting obligation. In the medium term, the national implementation of the CSDDD is to replace the LkSG.

Are mid-sized companies affected by ESG sanctions?

Directly, mainly through the CBAM, EUDR and EmpCo, because these rules are not tied to company size. The CSRD, CSDDD and LkSG usually affect mid-sized companies indirectly: large customers pass their obligations on to their suppliers through contracts and data requests.

Save money and nerves with VERSO

To ensure that companies do not approach the sustainable transformation too carelessly, the EU provides for “effective, proportionate and dissuasive” measures in any case.

In view of the possible sanctions, we are happy to believe this – and help you to correctly implement the guidelines and regulations that apply to you. Not only our top software, but also our experienced consultants and our specialized partners are at your side. Feel free to get in touch with us!

Subscribe to our newsletter!

Register now to arrange a free demo appointment and get to know our solutions at first hand.

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers
Get to know the software!

Der Aufbau der ESRS: SO berichten Sie CSRD-konform.
28.11.2024

Structuring an ESRS report: How to ensure CSRD compliance

Tens of thousands of companies are required to publish a CSRD compliant sustainability report for the first time. Many are now faced with over 1,000 data points and wondering: How do we turn this into a structured sustainability report? What is the structure of an ESRS report?

This article will guide you through the process and provide you with a checklist to help identify the key data points for your report.

Creating an ESRS report – What needs to be done?

For most companies, preparing a CSRD-compliant sustainability report is uncharted territory. So far, only a few have completed this process, meaning you are not alone. To understand the structure of an ESRS report, it is helpful to first familiarize yourself with the individual ESRS standards. The next step is to focus on the disclosure requirements and data points that are most relevant to your company. To support you in this process, we have prepared a practical checklist.

What do CSRD and ESRS require?

Being affected by the CSRD means that a company is required to publish a sustainability report as part of its management report. This sustainability report is not meant to be a marketing brochure but a comprehensive document covering environmental, social, and governance (ESG) topics.

A key aspect: Companies do not have the freedom to choose their reporting framework – the ESRS are the mandatory standards they must follow. Additionally, just like the management report, the sustainability report must be audited by external auditors. This makes it even more crucial to understand the framework, be familiar with the structure of the report, and ensure that you report on the correct, material data points.

How should I approach the double Materiality Assessment?

Speaking of key data points: The double materiality assessment is the core of the ESRS report.

Download the full blog post now and gain access to:

  • Tips for conducting the double materiality assessment,
  • An overview of the ESRS structure,
  • In-depth insights into the content of the ESRS standards, and
  • A checklist for identifying the key material data points.

Before we continue

The content on this website is the result of the work of people who immerse themselves in the world of ESG with much passion and care. We take the time to present complex topics in an understandable way and provide practical tips. To prevent our work from being copied or used as AI training material, we ask you to leave us your e-mail address for particularly extensive and detailed content such as this. You will then receive the article as a PDF directly in your mailbox.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Current ESG topics and legislative changes
  • Individual advice from the VERSO experts
  • News about VERSO
  • Trusted by 250+ customers

Sign up now!

Holzwürfel, die ein Diagramm mit steigendem Pfeil abbilden: Richtig gemacht, können Nachhaltigkeitesberichte zur Steigerung des Unternehmenserfolgs beitragen Rising bar chart made of wooden blocks symbolizing measurable progress and continuous improvement in a sustainability report.
19.11.2024

Sustainability Report – What Is It and What Do You Need to Know?

Some companies are intrinsically motivated to embed ESG within their organization, while others are driven by the CSRD requirements or aim to gain a competitive edge. For all of them, the sustainability report becomes a constant companion on their ESG journey. Here’s an overview of the key terms and requirements for reporting.

What is a sustainability report?

This is the first fundamental question to address. In their sustainability report, companies disclose information on:

  • Environmental aspects,
  • Social matters
  • Corporate governance

The report outlines how external factors impact the company and how the company’s activities affect the environment and society. The first report usually reflects the status quo. However, the report is meant to go beyond that: it also describes strategies, targets, and actions aimed at enhancing sustainability.

The length, structure, and thematic focus of sustainability reports can vary greatly. This depends on the standard you choose. In general, you are free to decide which reporting framework to follow – unless you are bound to mandatory reporting requirements, such as those under the CSRD. In that case, you must comply with specific guidelines and often follow certain standards, such as the ESRS.

Overview of the ESRS Standards

The European Sustainability Reporting Standards (ESRS) are designed to make sustainability reports more meaningful and comparable. All the details are available in the whitepaper.

Sustainability, ESG, CSR – What’s the difference?

When it comes to reporting, all three terms essentially refer to the same concept: addressing the fundamental responsibility of companies toward the environment and society – now and in the future.

In recent years, the term CSR (Corporate Social Responsibility) was widely used in Germany.

  • CSR describes a company’s responsibility for its impact on society.
  • In practice, the term was often used to cover all three dimensions of sustainability: environmental, social, and governance aspects.
  • The focus of CSR is more on the qualitative assessment of a company’s actions regarding sustainability, corporate values, and social engagement.

The term ESG has now become increasingly established.

  • ESG stands for Environmental, Social, and Governance.
  • The term originates from the financial sector and focuses primarily on assessing companies based on environmental, social, and governance factors.
  • Measuring sustainability follows a more quantitative approach.

The broader term sustainability is generally used synonymously with CSR and ESG. It also accurately describes the reporting process, as it covers sustainability across all areas of the business.

You can find more on this topic in our blog post “CSR, ESG, Sustainability – What’s the Difference?”.

When do I have to publish my first sustainability report?

With the new Corporate Sustainability Reporting Directive (CSRD), many companies will soon be required to publish a sustainability report. The reporting obligation is based on criteria such as the number of employees, revenue, and total assets.

Although the first report often requires significant effort and may contain only limited insights into progress and developments, our honest advice is: Start now!

Our CSRD factsheet helps you quickly find out if and when your company is subject to reporting requirements—and what your next steps should be.

Practical Guide: Ready for Your First CSRD Report

The first CSRD report is a major challenge, as the EU directive comes with numerous requirements and new standards. Our practical guide, including a checklist, helps you get started and prepare for the CSRD and ESRS.

How do I create a sustainability report?

The first sustainability report can be demanding. You’re likely doing this for the very first time, with little prior experience – targeted training can be a great help. You often have no benchmarks yet, no established processes or structures, and still need to find the right reporting software – based on our experience with customers, the list of challenges for a first report is long.

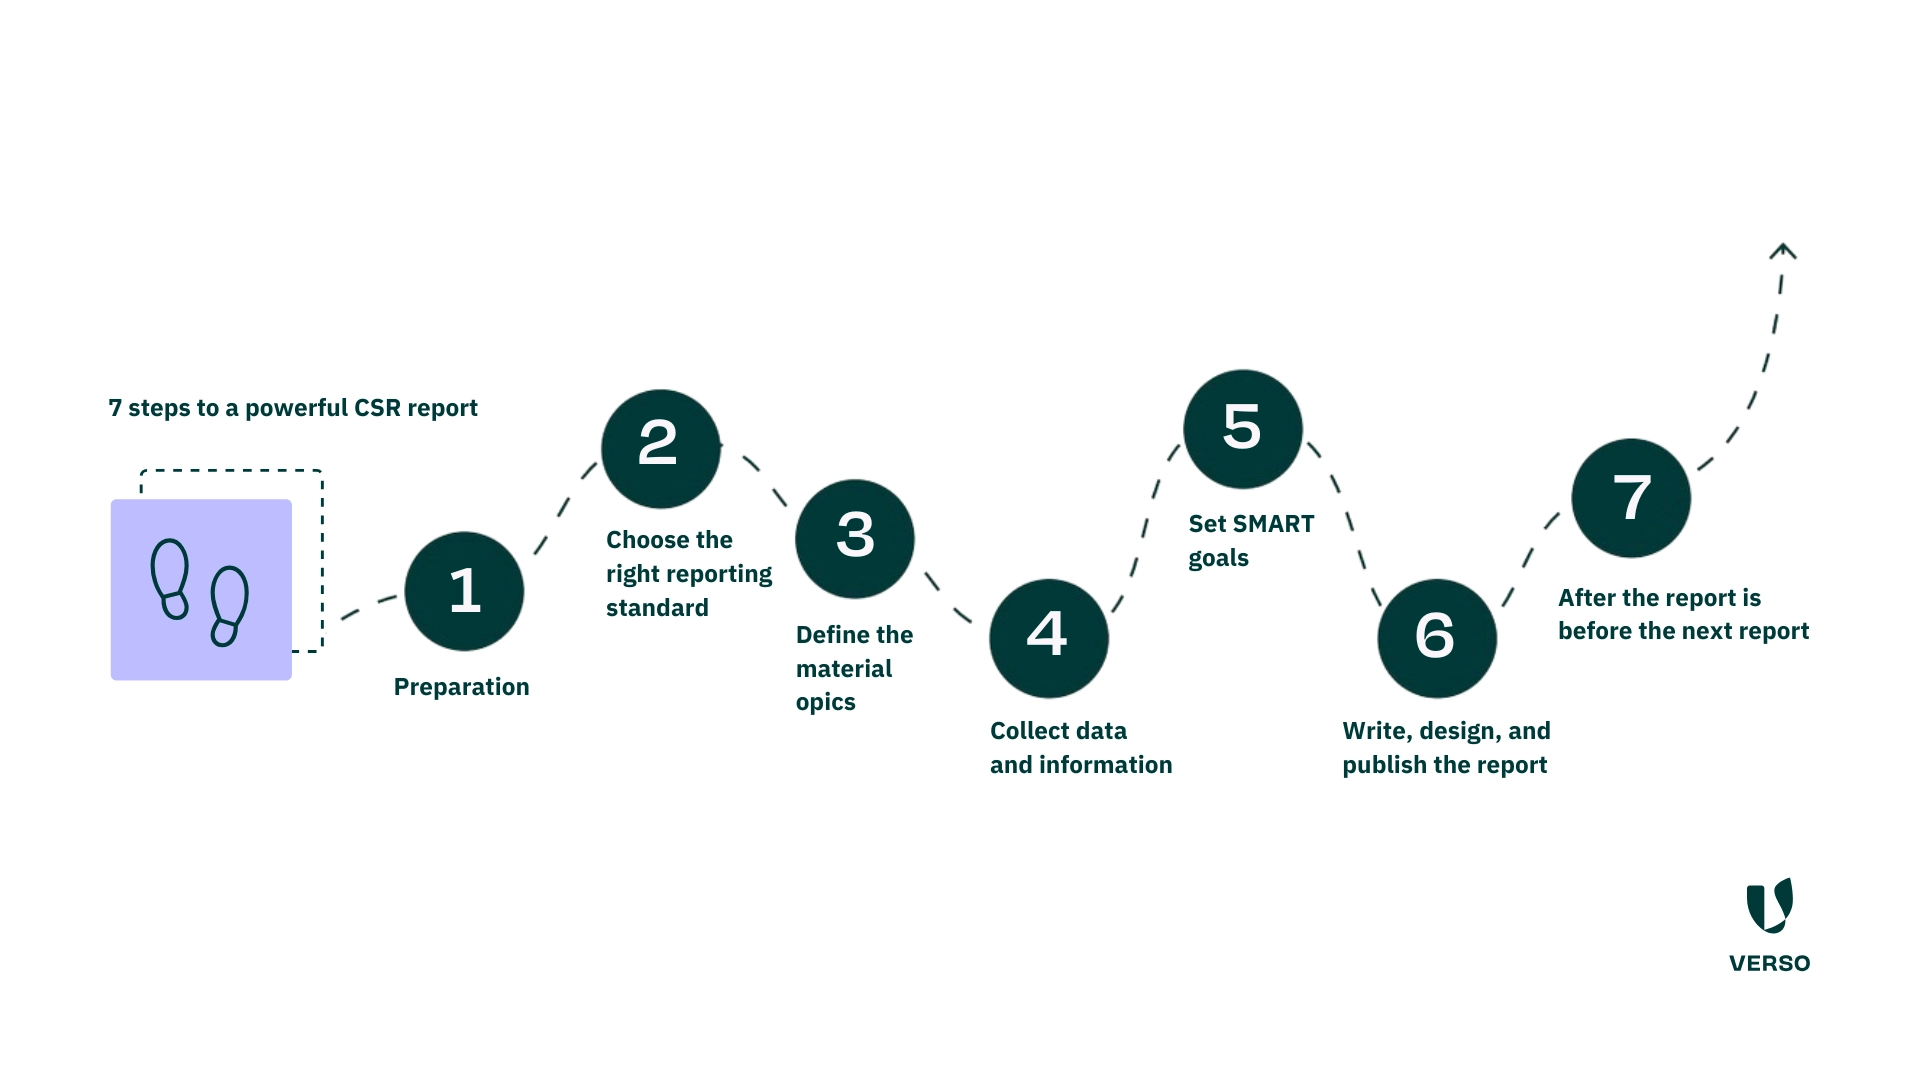
That’s where we come in: With the VERSO ESG Hub, you can create your sustainability report easily and efficiently. To help you get started, we’ve created a hands-on guide “7 Steps to Your CSR Report” that walks you through the process step by step toward a meaningful sustainability report.

And when it comes to software, you can rely on VERSO for your CSRD reporting: our CSRD Suite offers you an all-in-one solution.


7-step process showing the key stages of creating a sustainability report, from preparation and materiality analysis to data collection, goal setting, publication, and continuous improvement.

I’m new to the role of ESG Manager…

How do I establish sustainability management in my company?

If you’re just starting to work with ESG, this may sound familiar: You have a lot of ideas and initiatives in mind, but you need to align them within a clear, goal-oriented sustainability strategy. You’re also thinking about which targets are realistic and make sense for your business. On top of that, you still need the right processes and metrics to monitor progress.

And above all, three key questions arise:

  1. What does all of this mean for my company?
  2. How do I tackle such a huge topic?
  3. How do I justify my efforts and the necessary resources to management?

Our introductory blog articles on sustainability management are a great starting point. You’ll gain valuable insights into your role and responsibilities as a sustainability manager and get tips on how to communicate effectively with management – showing why sustainability matters for your business.

CSRD, SFDR, EU Taxonomy – What are they, and what’s the background?

With so many regulations, you’ve probably come across terms like CSRD, SFDR, EU Taxonomy, and ESRS. They are all part of the European Green Deal and closely interconnected. The EU aims to strengthen sustainability across the economy through these directives and regulations.

To comply with the CSRD, companies are required to report according to the ESRS—the European standards set by the EU. But how exactly do you apply these standards? Do frameworks like GRI or DNK also meet these requirements? You’ll find the answers in our ESRS Whitepaper.

The SFDR is a sustainability-related disclosure regulation for the financial sector. If you’re unsure whether it applies to your business and what steps to take, our SFDR Factsheet provides the guidance you need.

The EU Taxonomy is a classification system applied within CSRD and SFDR. It defines when an economic activity is considered green, sustainable, or environmentally friendly—creating clarity around sustainability claims. What this classification means for your business and your sustainability work is explained in our EU Taxonomy Whitepaper.

How can I make my company more sustainable?

Start taking action now! The more you can showcase (implemented) measures in your report, the more meaningful your sustainability report will be. Here are a few tips for effective sustainability initiatives in your company.

Communicate your sustainability journey right from the start—and be transparent about areas where action is still needed. This makes your ambitions credible and easier to understand. But be careful not to fall into common greenwashing traps when communicating your efforts. Not only could this damage your reputation, but the EU is also introducing specific anti-greenwashing regulations, such as the Green Claims Directive.


We support you in creating your sustainability report!

Preparing a sustainability report is especially challenging the first time. But with the right tools and solid knowledge, you can save both time and costs. We offer the perfect solution for both: Our training programs (available in german) provide fresh insights and help you become a sustainability expert. And with our ESG management software, you can quickly and efficiently collect all relevant sustainability data in one place.

* This information is summarized editorial content and should not be considered legal advice. VERSO assumes no liability. 

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Best practices in the areas of ESG and sustainable supply chains
  • Developed with expertise from 12+ years of sustainability management
  • Sustainability events and much more.

Get to know the software!

Nuvia Maslo im neuen Kurs der VERSO Academy, Fit for Sustainability
09.07.2024

What Specialists and Managers Should Know About Sustainability

ESG regulations, sanctions and real environmental threats are putting companies under increasing pressure. This means that sustainability must now be implemented in companies.

And in such a way that it does not become a bureaucratic monster. Because sustainability is not a spoilsport, but can create real business value. Read here to find out how this works and what you need to know as a specialist or manager.

Sustainability starts with specialists and managers

Sustainability ambitions must come from the management level.
Then it can create real business value with competitive advantages, cost savings and resilience.
At management level, the importance of the topic must be understood, priorities set and strategic decisions made for sustainability.
For specialists and managers, this means getting to grips with the topic of sustainability, acquiring knowledge and at least understanding the basics.
We give you 4 tips to help you successfully drive forward the sustainable transformation in your company.

Training tip: The new ESG course “Fit for Sustainability”

Learn everything that specialists and managers need to know about sustainability in our “Fit for Sustainability” online course.
The early bird phase is currently still running – register here for a 25% voucher!

4 tips for starting the sustainable transformation

1. find out about the role of companies in sustainability

Climate change is real.
The first effects are already being felt.
Extreme weather events are more extreme and occur more frequently.
There is a lot to be done to ensure that this planet remains liveable for future generations.
But what role do companies play in this?
Where are the most serious problems and how can we solve them?
You should be clear about this before you put sustainability on the agenda.
Because only then will you be able to win over your employees to the issue and only then will you have the know-how to implement measures with real impact.

2. familiarize yourself with the most important ESG regulations

With the Green Deal, the EU is bringing many laws and directives to the table that oblige companies to be more sustainable.
These include the CSRD reporting obligation, the CSDDD supply chain law and special regulations such as the EU Taxonomy, the SFDR regulation for the financial sector, the CBAM carbon border adjustment mechanism and the EUDR deforestation regulation.
In addition, there are also laws in Germany that require companies to deal with sustainability at all ESG levels, such as the German Supply Chain Act LkSG.
Of course, you don’t need to know all the directives and laws in detail.
However, an overview of the implementation deadlines, what needs to be done and which roles are required in the company is essential.

3. communicate sustainability transparently and without greenwashing

Regardless of whether you have to publish a sustainability report due to the CSRD obligation or would like to report on your sustainability activities voluntarily: Communicating sustainability is a fine line between correct and misleading.
What is communicated can quickly verge on greenwashing, and the CSRD also requires very comprehensive statements that have to be watertight.
Successful and legally compliant communication requires a good understanding of sustainability, of the company’s own activities, of sustainability communication and of the regulatory framework.

4. develop a sustainability strategy and use it to leverage potential for your company

The topic of sustainability and the associated laws and guidelines are often referred to as a “bureaucracy monster”.
But that doesn’t have to be the case: take a strategic approach to the topic and integrate sustainability firmly into your corporate strategy.
This will open up real opportunities for your company.
Because sustainable management makes your company resilient and fit for the future and opens up new business models and competitive advantages.

How do you get started? With knowledge building!

Now it’s time to get started!
At the VERSO Academy, we have the ideal course for you to gain knowledge on all these topics: You will efficiently learn everything important that specialists and managers should know about sustainability in the shortest possible time – tailored to your needs and potential.
After the training course, you can get started with the sustainable transformation straight away. Sounds good?
Get the
25 % Early bird discount – redeemable as soon as the course is bookable:

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers

Get to know the software!

Es lohnt sich für Unternehmen, wenn sie eine Nachhaltigkeitsstrategie entwickeln.
30.04.2024

Guide: How Do I Develop an Effective Sustainability Strategy for My Company?

Developing an effective sustainability strategy makes companies fit for the future and secures competitive advantages. This guide shows you step by step how to create a long-term plan for the future with social and environmental practices.

Developing a sustainability strategy is essential to make your company fit for the future. The crucial point here is that you can tackle the key issues in a targeted and structured manner on the basis of the strategy. In other words, minimize negative impacts, drive positive developments, reduce risks and seize opportunities.

This results in 5 clear advantages for your company:

  • Competitive advantages
  • Strategic planning
  • Better image
  • Greater customer loyalty
  • Greater attractiveness for talent

We present these benefits to you in more detail in the blog post “5 reasons for a sustainability strategy“.

Now we want to show you how to develop an effective sustainability strategy step by step. We want to dive deeper into the development of such a roadmap for the sustainable transformation of your company. This guide will take you through the entire process. We look at how you can

  • Identify key issues,
  • Define suitable measures and goals
  • and ultimately arrive at an effective strategy.

This gives you a holistic focus on ESG issues and the implementation of environmental, social and governance aspects.

How do I develop a sustainability strategy for my company?

“Lack of concrete goals and KPIs” – this is one of the biggest obstacles to sustainable transformation in companies, as the Bertelsmann Stiftung’s Sustainability Transformation Monitor 2024 shows. The lack of resources – both monetary and human – also plays a major role. A sustainability strategy provides the solution here. It contains concrete goals and key figures to monitor progress. And it focuses on the most important issues so that human resources can be deployed efficiently. However, there are other important steps in the development of an effective ESG strategy, which we will now take a closer look at.

1. status quo and key topics

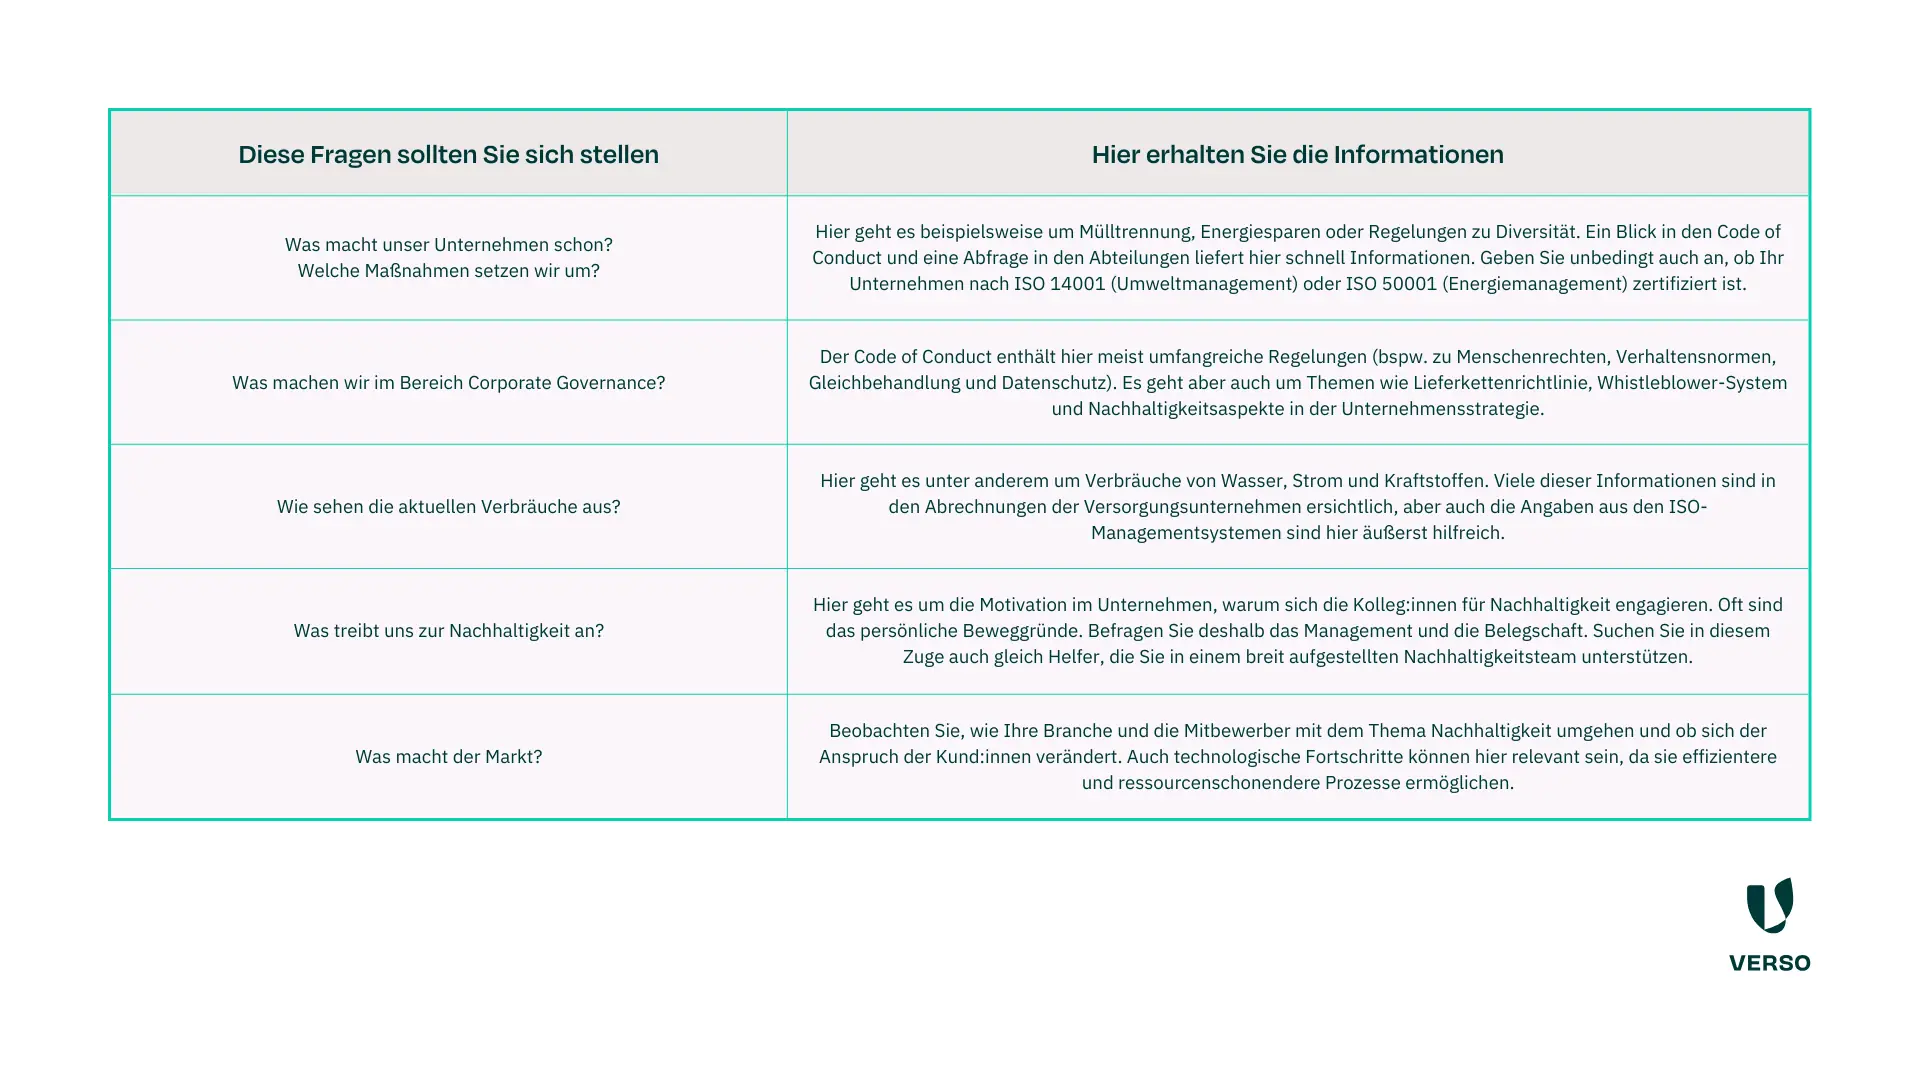
To know where you want to go, you first need to know where you stand. This is also the case when you are developing your sustainability strategy. You determine the current state of your company using a status quo analysis. This is your first data collection in the ESG area, so to speak, and should therefore be carried out thoroughly. The data and information form the basis for your future sustainability efforts. These topics, among others, play a role in determining the status quo:

Wichtige Fragen, um den Status quo Ihres Unternehmens im Bereich Nachhaltigkeit zu ermitteln, und wo Sie die Antworten finden.

The first time, the status quo analysis usually involves a great deal of effort. Numerous departments have to be involved. In some cases, the data is not available in the required form or has not yet been collected.

The VERSO ESG Hub simplifies and optimizes data management, as it is aligned with the ESG requirements of standards such as ESRS, GRI and DNK. The analysis of the current status serves as the basis for the following materiality analysis. Here you determine which sustainability issues are most important and where the greatest impacts, risks and opportunities (IRO) lie. If you publish a sustainability report in accordance with CSRD, you must carry out a double materiality analysis here.

A simple materiality analysis is also sufficient for a DNK report. Both procedures involve a certain amount of effort – the VERSO Sustainability Experts are therefore available to support you. The results of the materiality analysis are your fields of action and the specific IROs.

Activate the complete ESRS checklist here

What do companies have to report in accordance with the ESRS?
Once the overarching topics have been determined with the double materiality analysis, you can decide individually whether individual disclosure requirements and data points are relevant.
This checklist will help you with this.

2. define SMART objectives and suitable measures

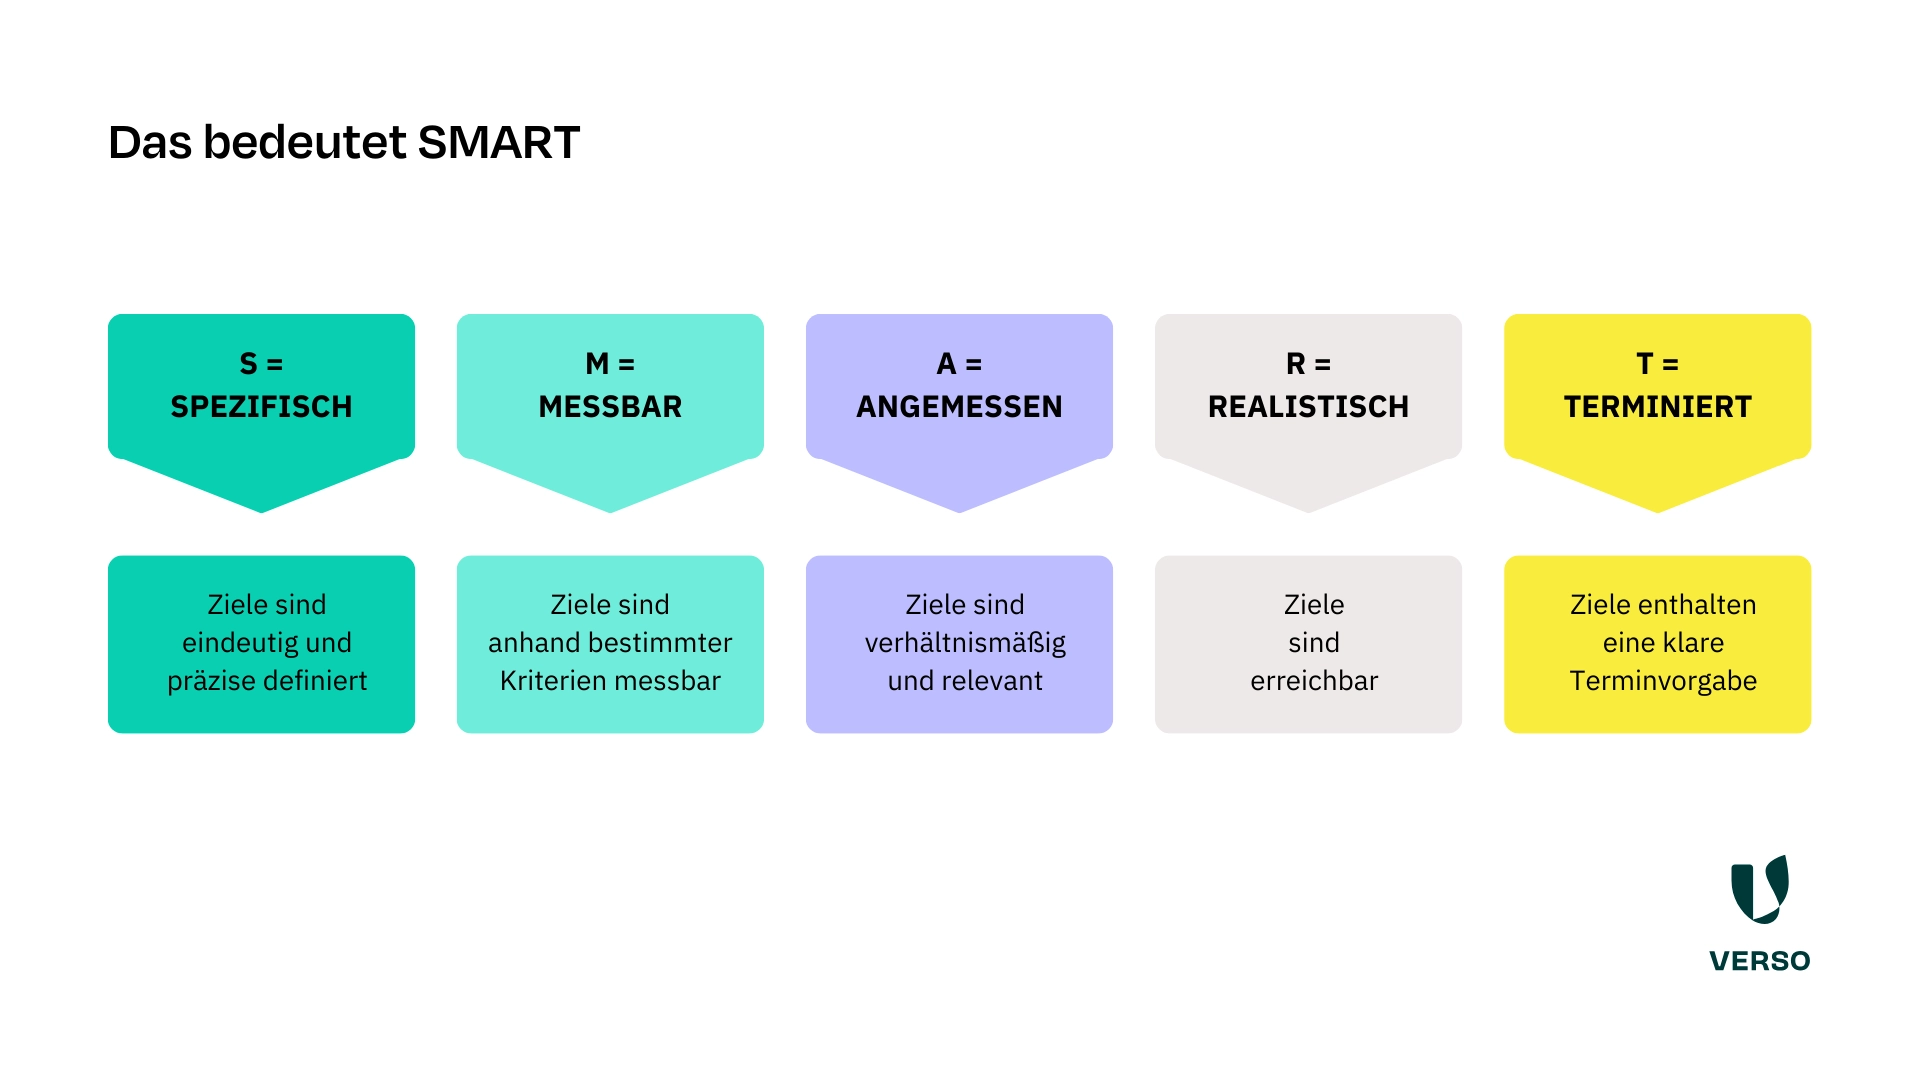
Based on the key topics, you define targets and KPIs for monitoring as well as suitable measures to achieve the targets set. You are at the center, so to speak, when you develop a sustainability strategy. When defining objectives, rely on science-based support. For example, use the GHG Protocol (Greenhouse Gas Protocol) or projects within the framework of the Paris Climate Agreement as a guide. You can find industry-specific assistance from the Science Based Targets Initiative (SBTi), for example. Make sure that you set yourself SMART targets. This method originates from project management. SMART is the acronym for Specific, Measurable, Achievable, Reasonable, Time-bound.

Setzen Sie sich SMARTe Ziele. SMART steht für spezifisch, messbar, angemessen, realistisch und terminiert.

The goals in the area of sustainability should not be detached from the corporate goals. Otherwise, conflicts of objectives can quickly arise. Instead, it is a good idea to integrate your ESG goals into the overall strategy. After the objectives, the headache continues – now it’s a question of what measures you want to use to achieve these objectives. Involve your employees, but also other stakeholders and experts. They are more likely to recognize solutions as they are more directly affected by the problems. Be aware that not all measures can be implemented company-wide. For some, it makes sense to implement them throughout the entire company. However, other measures are more specific and are only suitable for a particular department. You should formulate such measures directly with the employees concerned.

3. create an awareness of sustainability throughout the company

Sustainability is a company-wide team project. All departments are needed, for example, to implement measures, define new targets and provide data for ESG reporting. For this reason, it is also important to create a shared awareness of sustainability. The best time to build this is when you are developing your sustainability strategy. With a vision and mission for the sustainability area, you can give the topic the necessary importance.

These questions will help you to develop a meaningful statement that evokes emotions and motivates your employees:

  • What is our vision of the future?
  • What do we want to achieve as a company?
  • What future do we see for our company?
  • What values do we have as a company?

To give sustainability the importance it deserves in your company, you should not see it as a separate strategy. Instead, integrate the topic into the overall strategy. This will allow you to anchor the ambition to lead your company into a more sustainable future in all areas and processes of the company. And very importantly: talk about your company’s ambitions.
Get everyone on board. Communicate the vision and mission. Explain what drives you and what you want to achieve. This will create a shared awareness of sustainability.

Your overview of the new Green Claims Directive

New obligations for all those who advertise with terms such as “climate neutral”: The Anti-Greenwashing Directive sets barriers.
What you should know now.

4. it’s time for implementation: control is the be-all and end-all

The development of your sustainability strategy is complete – now it’s time to implement it. You should see ESG management as a process. It will take many years until you achieve your medium and long-term goals. You need to take a long breath. You will probably even have to adjust your measures and targets as new findings and developments (regulations, products, business models) emerge over time. By constantly reviewing and measuring your measures using suitable KPIs, you can keep control of your progress and the entire process at all times. Deviations from the target become apparent at an early stage and you can make adjustments. A tool such as the VERSO ESG Hub is also ideally suited to this challenge and simplifies your sustainability management enormously.

Transparency is also an important factor during implementation in order to further increase awareness of sustainability among stakeholders and employees in particular. Motivation is quickly diminished if you are only involved at the start but then hear nothing more about the topic. It is therefore also important to talk openly about the results to date – both negative and positive. This promotes trust and understanding, increases motivation and facilitates collaboration.

Develop a sustainability strategy: VERSO supports you!

VERSO supports you with expertise and software in the strategic implementation of sustainability in your company. Our VERSO Sustainability Experts will accompany you throughout the entire process – from stocktaking and materiality analysis to sustainability management and reporting. The VERSO ESG Hub offers you a comprehensive solution for holistic sustainability management. And if you want to acquire further knowledge, you can attend training courses at the VERSO Academy. This allows you to implement your sustainability strategy independently – but still receive reliable support.

Does that sound like what you’re looking for?
Feel free to contact us for more information.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers

Get to know the software!

Stakeholder-Anforderungen von ESG-Informationen an KMU
12.02.2024

5 Reasons Why A Sustainability Report Is Also Worthwhile for SMEs

Many companies – large and small – are affected by sustainability regulations such as the CSRD, the LkSG or the European supply chain law CSDDD. But what about those that are not subject to these regulations? Are they exempt from reporting?

Watch out: Not being directly affected does not mean that you do not have to deal with sustainability! We explain here why SMEs also have to provide sustainability data and what information is required.

Which stakeholders request ESG data from SMEs

1. business partners create transparency in the supply chain

Are you a supplier to another company? Many SMEs supply larger companies that fall under the LkSG (Lieferkettensorgfaltspflichtengesetz) and are or will be affected by the EU CSRD (Corporate Sustainability Reporting Directive) and CSDDD (Corporate Sustainability Due Diligence Directive).

Large companies not only have to make their own ESG information transparent, but also that of their suppliers.

This means that you are also affected by the requirements of the regulations and will be asked by your customers for comprehensive sustainability information.

As a result, you have to undergo extensive due diligence checks, such as the EcoVadis sustainability assessment, which identifies potential risks for people and the environment in the supply chain.

Incidentally, it is not only you as a supplier who must provide evidence, but often also sub-suppliers.

Your customers are also bound by industry-specific guidelines and laws.
Sustainability information from the supply chain is also required from this side.
Examples of this include the Agricultural Organizations and Supply Chain Act (AgrarOLkG), the chemical industry standard or the industry-specific guidelines of the OEC.

2. financial sector pays more attention to sustainable investments

SMEs that are supported by investors or have received project-related investments should definitely be prepared for ESG inquiries.
The reasons for this:

  • Due to the SFDR (Sustainable Finance Disclosure Regulation), financial market players and financial advisors are obliged to provide ESG information on financial products and services.
  • Investors are themselves capital market participants and must report on sustainability goals and positioning within the financial sector.
  • Rating agencies now also include ESG criteria in their investment ratings.
  • Prior to the final M&A transaction, the sustainability strategy is reviewed – if not already requested in advance, measurable sustainability indicators are required from you by then at the latest.

All information about the SFDR

The Sustainable Finance Disclosure Regulation (SFDR) is one of the EU’s levers for promoting a sustainable economy. Get an overview of the SFDR, the categorization of financial products and the disclosure requirements.

3. banks require ESG disclosures in loan and funding procedures

If you want to apply for a loan or a grant from the bank, you will need a number of documents.
In the past, it was mainly about creditworthiness, business concept, collateral and the like.
Today, the issue of sustainability also plays a decisive role.

This is because banks need sustainability information from you when granting loans in order to meet the requirements of the European Banking Authority (EBA) and the German Federal Financial Supervisory Authority (BaFin).

In addition, banks are increasingly adhering to self-imposed frameworks and sustainable finance targets.

In practice, this means that lending costs are directly influenced by your ESG rating: better rating, cheaper loan.

This data decides on loans

Read this article to find out how ESG data affects financing and what data companies need to provide now to ensure their loan applications continue to be approved.

4. insurance companies also include ESG risks in their financial statements

Insurance companies also rely on and request ESG data from customers. Two perspectives need to be understood here: Firstly, (re)insurers also fall under the CSRD reporting obligation.

They must therefore report on the status quo of their sustainability ambitions themselves.
This also includes the customer area, for which your insurer naturally needs information from you as a customer.

The second perspective is about the insurance risk when you want to take out a new insurance policy.

It is common practice here to first assess the risk potential of an insured person. Sustainability risks are now also taken into account. Anyone who does not have this issue on their radar may be classified as having a higher insurance risk and lower insurance benefits.


5. customers and partners expect proof of ESG efforts

New partnerships, collaborations and tenders are increasingly demanding certifications that prove a company’s sustainability ambitions.

When you enter into negotiations, you need to be well prepared:

  • No Open Doors without ESG certifications: In addition to known information security standards, for example, certifications from the ESG sector are increasingly a prerequisite for a serious discussion.
    Go through the assessments at an early stage – they are often lengthy and cannot be “handed in quickly”.
  • Sustainability and ESG criteria in the tendering process: If there is a tender, your company could fall out of the selection process due to a missing or unsound sustainability strategy.
    You can prove this with recognized ESG certificates, among other things.
    With sustainability and ESG criteria in tendering processes, companies want to ensure that ecological and social standards are adhered to in the supply chain right from the start.

In addition to special ESG certifications, ESG criteria are also asked for in other quality standards that have a high priority in the industry and are actually “only” concerned with corporate processes:

  • Fairtrade
  • Organic certifications
  • Employer rankings
  • ISO standards
  • …

CSRD compliance made easy

From the CSRD basics to the finished report: Our practical software package guides you step by step to CSRD compliance!

How do SMEs best prepare for sustainability requirements from stakeholders?

As you can see, sustainability issues come from every corner. You not only have to collect and communicate ESG data to fulfill legal requirements – keyword: LkSG, CSDDD and CSRD-compliant.

Your stakeholders also ask for this data for a variety of reasons. The problem with these queries is that if SMEs are affected by one or more of these scenarios and are not prepared for them, this usually means a lot of work. This is because very different information is required from different stakeholders. They are confronted with different reporting standards and find themselves in a flood of questionnaires.

However, you can avoid these problems with a voluntary sustainability report.
It is best to report in accordance with a recognized standard that is suitable for your company, such as the DNK, the GRI Standards or the ESRS – the latter will enable you to meet the regulatory requirements of the CSRD in the future. Frameworks such as the SDGs or the UN Global Compact also form a good basis for the sustainability report.

EFRAG is currently also working on its own voluntary standards(VSME) for SMEs, which are adapted to the size, resources and needs of these companies.
The advantages of a voluntary report in a nutshell:

  • As a rule, you already collect all the important data that you also need for other purposes.
    In the best case even in a single tool, in which you can also control measures and write the report.
  • In the case of inquiries, the report already contains most of the required information, giving you more time for detailed questions.
  • If you do have to report later, you are already optimally prepared for CSRD, LkSG and CSDDD!
  • Although this may sound like a lot of effort at first, the introduction of ESG structures brings with it great opportunities: innovation and long-term growth are promoted, risks are minimized and, not to forget, you also consolidate and strengthen relationships with your customers.

Step-by-step to the sustainability report

A meaningful sustainability report can be quite a challenge. Where do you start? What data is important? And how should the CSR report be published? Our practice-oriented playbook answers your questions.

Do you want to be prepared for the next request?

The voluntary sustainability report puts you ahead of the game!
If you have any questions about the sustainability report or the legal requirements, we are here for you – with over 12 years of experience in sustainability management.

* This information is summarized editorial content and should not be construed as legal advice. VERSO accepts no liability.

Subscribe to our newsletter!

Sign up and receive regular news about:

  • Pragmatic all-in-one solution for ESG reporting, climate and supply chain management
  • Individual advice from the VERSO experts
  • Developed with expertise from 12+ years of sustainability management
  • Trusted by 250+ customers

Get to know the software!

Secret Link